Economy
Expert charts path for effective power reforms


As the nation continue to grapple with electricity challenges, irrespective of the reforms being implemented , stakeholders and economists in the country have said the Power sector reform in the country remains a long-term and incremental process rather than a quick fix.
They based their submission on the sector’s complexity, political economy constraints, and institutional weaknesses, which would make the progress gradual rather than instant, warning that without decisive action to address structural inefficiencies, improve governance, and ensure fiscal discipline, the current trajectory will remain unsustainable.
An economist and Chief Executive, Center for the promotion of Private Enterprise (CPPE), Dr. Muda Yusuf, noted that despite multiple reform efforts over the years, the sector continues to face deep structural, financial, and governance challenges.
These challenges, he said, are multi-dimensional, spanning political economy constraints, tariff distortions, weak investor capacity, transmission bottlenecks, and a persistent liquidity crisis across the value chain.
He argued that the inability to implement a fully cost-reflective tariff regime—largely due to social and political sensitivities following recent macroeconomic reforms—has entrenched subsidy dependence and widened the sector’s financing gap, thereby making government intervention to become unavoidable in the short term to prevent system collapse and sustain electricity.
He listed recent macroeconomic reforms, including foreign exchange unification and fuel subsidy removal, to have further complicated the reform environment by heightening cost-of-living pressures and intensifying resistance to tariff adjustments in the power sector.
“However, without cost-reflective pricing, the sector is unable to generate sufficient liquidity to sustain operations or attract new investment. The resulting subsidy burden has forced government to repeatedly intervene financially, effectively transferring inefficiencies and revenue shortfalls onto the public balance sheet,” the CPPE boss said.
Yusuf made it known that the current trajectory, characterised by rising sector debt currently at about ₦4 trillion, is fiscally unsustainable without deeper structural corrections, improved transparency, and gradual but credible reform implementation.
Giving an analysis of the sector, yesterday, the CPPE helmsman advocated for a balanced approach-one that combines short-term government support with medium- to long-term structural reform. This, he noted, is essential to building a financially viable, reliable, and inclusive power sector that can support Nigeria’s economic growth and development.
According to Yusuf, the current financing model for the sector is not sustainable. He’s arguement is based on the sector’s liabilities which have risen to nearly ₦4 trillion and continue to grow.
He therefore warned that there is an urgent need to ensure that all outstanding claims are properly verified; subjected to rigorous audit and managed transparently and credibly.
“Nigeria’s experience with fuel subsidy regimes demonstrates the vulnerability of subsidy systems to abuse and malpractice. Strong oversight and accountability mechanisms are therefore essential to prevent similar outcomes in the power sector,” Yusuf warned.
He noted that one of the major problems that has. Continued to weigh on the finances of the sector is the lack of a cost reflective tariff regime.
To address this, Yusuf, a policy analyst, admonished for the implementation of a phased and predictable transition toward cost-reflective pricing, with targeted social protection for vulnerable consumers.
This, he said, should be backed by a strong governance and accountability regime which will be targeted at improving transparency in subsidy management, debt verification, and financial settlements.
Importantly, he further added, is the urgency in addressing the distribution sector weaknesses. This will be by way of enforcing performance benchmarks for Discos, including recapitalisation, technical upgrades, and loss reduction.
The CPPE boss also canvassed for a reform in transmission management by exploring alternative management or concession models for TCN to improve efficiency and investment.
“It is important to support decentralization and renewables; encourage state-level initiatives, independent power projects, and renewable energy adoption to reduce pressure on the national grid. Also, we need to limit fiscal exposure as government financial support should be clearly time-bound and linked to measurable reform milestones,” Yusuf argued.
Economy
Dangote: Fed. govt.’s economic reforms driving Nigeria’s economic recovery, restoring investors’ confidence
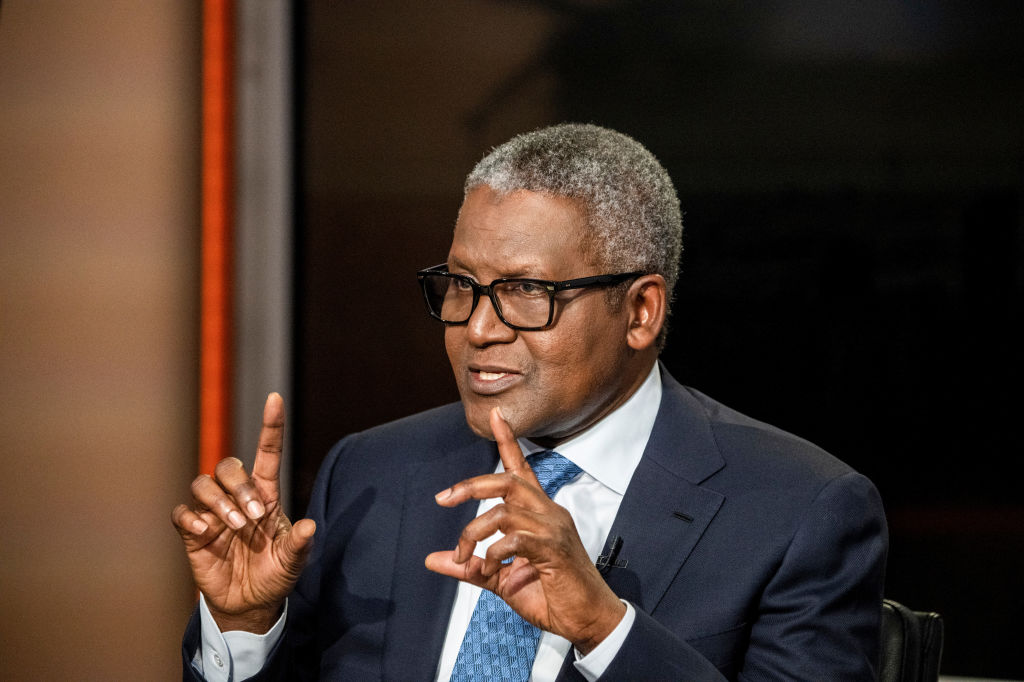
· Says sustained reforms, policies will make Nigeria Africa’s most attractive investment destinations
· Ties Refinery’s progress to govt.’s supportive investment, domestic industrialisation policies
By Oluwayanmife Lucas
President and Chief Executive, Dangote Industries Limited (DIL), Aliko Dangote, has commended the Federal Government for implementing bold and transformative economic reforms that are repositioning Nigeria for sustainable growth, strengthening investor confidence, and accelerating the country’s economic recovery
Dangote hailed the ongoing fiscal, monetary, and regulatory reforms of the government, insisting that it has contributed significantly to improving macroeconomic stability, enhancing productivity across key sectors, increasing Nigeria’s attractiveness as an investment destination, and fostering a more resilient business environment. He noted that the positive outcomes emerging from the reform agenda underscore the importance of consistent, market-driven policies in advancing national development and economic prosperity.
“The economic reforms being implemented by the Federal Government are beginning to yield tangible results. We are witnessing improved economic activity, stronger investor confidence, increased industrial productivity, and a more resilient business environment. These measures are laying a solid foundation for sustainable economic growth and long-term prosperity for Nigeria,” Dangote stated.
According to the DIL boss, the reforms have created a more enabling operating environment for businesses, particularly large-scale manufacturing and industrial enterprises that are critical to economic diversification, job creation, foreign exchange generation, and national competitiveness. He added that government initiatives aimed at improving efficiency, promoting investment, enhancing transparency, and supporting domestic production are providing a solid framework for industrial expansion.
“We commend the Federal Government for its courage and determination in implementing reforms that are essential for economic transformation. While every reform process comes with initial challenges, the benefits are increasingly evident in stronger economic indicators, improved business confidence, and renewed investor interest in Nigeria,” he said.
Dangote further observed that the government’s favourable policy environment has supported the continued growth and efficient operation of the Dangote Petroleum Refinery and Petrochemicals complex, Africa’s largest integrated refining and petrochemical facility. He noted that policy measures designed to strengthen local refining capacity, reduce import dependence, improve energy security, and encourage value addition have contributed meaningfully to the refinery’s success and Nigeria’s broader economic development objectives.
“The progress being recorded at the Dangote Petroleum Refinery and Petrochemicals complex is closely linked to a policy environment that encourages investment, supports domestic industrialisation, and promotes self-sufficiency. These reforms are helping Nigerian businesses to plan with greater certainty, invest with confidence, and compete effectively on the global stage,” he added.
He stated that the refinery’s increasing production capacity and expanding export footprint are contributing significantly to Nigeria’s economic resurgence by generating foreign exchange earnings, creating employment opportunities, strengthening local supply chains, and positioning the country as a leading energy and manufacturing hub.
Reaffirming the Group’s commitment to supporting the Federal Government’s economic agenda, Dangote assured that the DIL would continue to invest in strategic sectors, drive innovation, promote industrial development, and create sustainable employment opportunities.
“Our vision has always been to support Nigeria’s economic development through transformative investments. Today, we are witnessing how the combination of private-sector commitment and decisive government policies can unlock unprecedented opportunities for national growth. The refinery, petrochemical operations, fertiliser production, and our other industrial investments are helping to build a more self-reliant, competitive, and prosperous economy,” he said.
He expressed confidence that sustained reforms, policy consistency, and stronger collaboration between the public and private sectors would further stimulate economic growth, attract increased foreign direct investment, and reinforce Nigeria’s position as one of Africa’s most attractive investment destinations.
“Nigeria is on the path to becoming one of the world’s leading industrial and economic powers. With continued policy consistency, robust private-sector participation, and investment-led growth, the future of our economy is exceptionally bright,” Dangote concluded
By Oluwayanmife Lucas
Nigeria’s external reserves have reached an 18-year high of $53.99 billiion on September 2. The reserves position puts the naira on course for its best year since 2018 ahead of FTSE Russell reinclusion on September 21.
According to data from the Central Bank of Nigeria (CBN), external reserves were at $53.1 on August 24. The current reserves position is far higher that CBN’s projected $51.04 billion year-end target, and will cover over 12 months import for the economy.
Nigeria’s external reserves, which provide the CBN with the capacity to support the local currency and meet external obligations, have continued to rise steadily. Further analysis showed that the liquid portion of the external reserves stood at $52.5 billion.
Brent crude yesterday traded around $95.5 per barrel—above Nigeria’s 2026 federal budget benchmark of $64.85—the price rebound would largely bolster the country’s fiscal revenues.
As an oil exporter, Nigeria continues to earn more petrodollars and to support naira stability ans bolster external reserves.
In its economic projections for 2026, the CBN targeted stronger oil earnings, foreign exchange market reforms and improved external capital inflows to achieve year-end reserves target.
Analysts said the current reserves position reinforces the steady growth in Nigeria’s external buffers.
The founder/Chief Executive Officer of the Centre for the Promotion of Public Enterprise (CPPE), Dr Muda Yusuf, earlier hinted at a positive outlook for Nigeria’s external reserves as he does not see anything derailing the forex and fiscal reforms that have brought about stability and improvement in external reserves.
Yusuf said, ‘’Well, the outlook for me is positive because I don’t see anything derailing these forex reforms, fuel subsidy etc. It is these reforms that have brought about stability”.
CBN data sfurther showed that Nigeria’s external reserves maintained a steady upward surge in recent months.
The reserves started June at $49.80 billion and crossed the $50 billion mark by June 5, reaching $50.12 billion.
On June 15, reserves had increased further to $50.81 billion before rising to current position. The reserves stood at $51.9 billion on July 31, and contrinued.
The sustained increase reflects stronger foreign exchange inflows and improved liquidity conditions in the country’s external sector.
The CBN Governor Olayemi Cardoso, said: “This strong buffer continues to reinforce investor confidence in the Nigerian economy and support exchange rate stability.”
The CBN’s decision to clear over $7 billion unsettled FX backlogs raised investors’ confidence in the economy, supporting dollar inflows and foreign reserves accretion, Cardoso said.
The CBN boss had explained that although he had no idea where the fund for the backlog clearance would come from, when he assumed office, but he believed it was the right thing to do, and gave investors his word.
He said: “Credibility is at the heart of any central bank. If you don’t have credibility, people do not trust you and they do not invest in your economy. When I took office, I made a promise we would pay the backlog, the verifiable backlog of monies that were owed by Nigeria to third parties.”
By Olamide Akintunde
Experts in corporate governance, finance and public policy have said Nigeria must institutionalise good governance, sustain economic reforms and strengthen collaboration between the public and private sectors to accelerate economic growth and realise its ambition of becoming a $1 trillion economy.
The call came at the 2026 National Corporate Governance Summit themed “Implementing Good Governance for Economic Acceleration: Consolidating Public and Private Sector Partnership,” organised by the Institute of Directors (IoD) Centre for Corporate Governance, the Financial Reporting Council of Nigeria (FRC), the Ministry of Finance Incorporated (MOFI) and the Institute of Chartered Secretaries and Administrators of Nigeria (ICSAN).
Speaking on the theme, the Special Adviser to the President on Economic Affairs, Dr. Tope Fasua, who represented the Vice President, Kashim Shettima, said President Bola Tinubu’s administration remained committed to implementing reforms capable of building a resilient and competitive economy.
He said the government’s economic reforms including foreign exchange reforms, tax reforms and subsidy removal must be complemented by strong corporate governance in both public institutions and private enterprises.
“The public sector can create the enabling environment through reforms, but it is the private sector that translates those policies into investments, jobs and wealth creation. Both sectors must operate with integrity, accountability and transparency,” he said.
Fasua emphasised that governance should not be treated as a mere compliance exercise but as the foundation upon which investor confidence and sustainable economic development are built.
Speaking on the sidelines of the summit, he explained that the Federal Government’s reforms were designed to create long term economic transformation rather than deliver short term political gains, while calling for greater support for domestic investment and industrialisation.
Delivering the keynote address, the Chairman of Nigerian Breweries Plc, Mrs. Juliet Anammah, described the summit’s theme as timely, saying good governance must move beyond compliance and accountability to become a strategic tool for driving Nigeria’s economic rebirth. She maintained that stronger partnerships between government and the private sector would be critical to achieving sustainable economic acceleration and improving the quality of life of Nigerians.
According to her, the country’s immediate objective should be to move from a lower-middle-income economy to an upper-middle-income economy through sustained industrialisation, innovation and long-term policy implementation.
She acknowledged that the Federal Government had undertaken bold reforms, including fuel subsidy removal, foreign exchange unification and bank recapitalisation, saying the difficult decisions had helped stabilise the economy.
While noting that macroeconomic stability was encouraging, Anammah said it was not the final destination.
“Stabilisation is not the end goal. The destination is economic rebirth that improves household incomes, creates quality careers, expands access to healthcare and education and delivers reliable infrastructure,” she said.
Drawing lessons from countries such as Vietnam and Morocco, she argued that Nigeria must embrace industrialisation by producing more sophisticated and value-added products instead of relying on primary commodities.
She noted that sectors such as petrochemicals, agro-processing, automotive, renewable energy and manufacturing already possess enormous growth potential but require consistent industrial policies supported by sound governance to unlock higher levels of economic complexity.
According to her, policy inconsistency remains one of Nigeria’s greatest development challenges, urging governments at all levels to sustain industrial policies beyond political administrations.
She also advocated stronger competition among states, independent evaluation of industrial policies and closer collaboration between government and the private sector to deepen investment and accelerate economic growth.
She concluded that achieving meaningful economic acceleration would require strong corporate governance, sustained industrial policies and close collaboration between government and the private sector, noting that only through such coordinated efforts can Nigeria transition from an economy driven by informal livelihoods to one characterised by productive industries, quality careers and rising prosperity for its citizens.
Earlier, Chairman of the Board of Governors of the IoD Centre for Corporate Governance, Dr. Uche Eke, said the summit deliberately shifted the conversation from governance principles to implementation, stressing that sustainable economic growth would only be achieved when sound governance becomes embedded across both public institutions and private enterprises.
He explained that Nigeria had spent years identifying governance challenges and developing frameworks, stressing that the time had come for practical execution.
“We have stayed too long articulating the issues. The focus now is implementation. We must embed sound corporate governance practices in both public institutions and private organisations to guarantee sustainability beyond current leadership,” he said.
Eke noted that the summit sought to build national consensus among regulators, government institutions and the private sector on practical governance reforms capable of improving transparency, accountability and economic competitiveness.
He stressed that merit, competence and diversity should determine appointments into leadership positions rather than nepotism or political considerations.
“If Nigeria is serious about building a one trillion dollar economy, we must consistently place the right people in leadership positions, promote diversity of skills and hold leaders accountable for results,” he said.
Also speaking, Managing Director and Chief Executive Officer of MOFI, Dr. Armstrong Takang, said government alone cannot build the economy Nigeria desires, stressing that strong corporate governance is the foundation for effective public-private partnerships, investor confidence and long-term economic development.
He argued that contrary to the belief that government should not participate in business, successful economies such as China had demonstrated that well-governed state-owned enterprises could become major drivers of investment, industrialisation and economic growth.
Takang said MOFI’s recent experience showed that institutions with strong corporate governance frameworks consistently attracted greater investment and delivered better value creation.
According to him, governance reforms introduced across MOFI’s portfolio companies had significantly improved investor confidence and strengthened the performance of government-owned assets.
He cited initiatives including the MOFI Real Estate Investment Fund and the proposed Metro Rail Infrastructure Programme as examples of projects attracting institutional investment because of strong governance structures.
“Government alone cannot build the economy we desire. We need partnerships with the private sector and institutional investors, and corporate governance remains the common denominator that inspires confidence and mobilises capital,” he said.
Stakeholders and participants at the summit agreed that sustaining reforms, strengthening institutions and entrenching transparency across both public and private organisations would be critical to accelerating economic growth, boosting investor confidence and positioning Nigeria to achieve its long-term development ambitions.


-
 Art & Life9 years ago
These ’90s fashion trends are making a comeback in 2017
-
Business9 years ago
The 9 worst mistakes you can ever make at work
-
Entertainment9 years ago
The final 6 ‘Game of Thrones’ episodes might feel like a full season
-
Art & Life9 years ago
According to Dior Couture, this taboo fashion accessory is back
-
Entertainment9 years ago
The old and New Edition cast comes together to perform
-
Entertainment9 years ago
Mod turns ‘Counter-Strike’ into a ‘Tekken’ clone with fighting chickens
-
 Law & Crime10 months ago
EFCC vs Yahaya Bello: Court adjourns ₦80.2b alleged fraud trial to Nov 11
-
Sports9 years ago
Phillies’ Aaron Altherr makes mind-boggling barehanded play