Finance
IMF backs CBN’s rate reset, urges Nigeria to raise non-oil revenue

By Our Correspondent
The International Monetary Fund (IMF) has backed the Central Bank of Nigeria’s gradual reduction of interest rates, saying the move is appropriate following significant progress in bringing inflation down, notwithstanding the fact that monetary policy remains tight.
The Fund also urged the Federal Government to increase revenue from non-oil sourcels to create more resources for education, healthcare and infrastructure, while pursuing reforms to attract private investment and create jobs.
The Director of the IMF’s African Department, Zeine Zeidane, gave the advice during the presentation of the Fund’s Regional Economic Outlook for Sub-Saharan Africa on the sidelines of the ongoing IMF/World Bank Annual Meetings in Bangkok, Thailand.
Zeidane said Nigeria had made significant progress in reducing inflation after a period of high price increases, creating room for some adjustment in monetary policy.
He described the decision to reduce interest rates as appropriate but cautioned against interpreting it as a move towards an accommodative monetary policy.
According to him, the overall policy stance remained tight, suggesting that the authorities were adjusting monetary conditions gradually rather than abandoning efforts to control inflation.
The position provides an important signal for businesses and investors as they assess the likely direction of borrowing costs, credit conditions and economic activity in Nigeria.
Speaking on the growth outlook, the Deputy Director of the IMF’s African Department, Montfort Mlachila, said Nigeria’s economy was benefiting from improved oil prices, stronger foreign exchange earnings, higher external reserves and increased liquidity.
Mlachila said the Fund had raised its growth forecast for Nigeria to 4.2 per cent in 2026 from four per cent previously, while projecting growth of 4.3 per cent in 2027.
He attributed the improved outlook partly to the more favourable external environment, increased foreign exchange availability, falling inflation and the performance of the services sector.
The IMF’s assessment suggests that stronger oil earnings and improving macroeconomic conditions are supporting economic activity, although sustaining growth will require reforms that broaden the sources of government revenue and attract more investment.
Zeidane advised the Federal Government to mobilise more revenue from outside the oil sector to strengthen public finances and provide more resources for essential services.
He said higher domestic revenue would create fiscal space for investment in education, healthcare and infrastructure.
The advice comes against the background of Nigeria’s exposure to fluctuations in international oil prices and competing demands on government revenue.
Zeidane also called for continued structural reforms to improve governance, the business environment and Nigeria’s integration with international markets.
He said Nigeria had a large market, a dynamic population, young entrepreneurs and a technology-aware workforce that could make it attractive to private investors.
However, he said these advantages needed to be supported by reforms that would make it easier for businesses to invest, expand and create jobs.
The IMF’s recommendations place domestic revenue mobilisation and private-sector investment at the centre of Nigeria’s efforts to sustain economic growth.
Zeidane advised Nigeria and other African countries to protect vulnerable households from rising living costs through targeted assistance rather than broad fuel-price subsidies.
He said general energy subsidies were expensive and often benefited wealthier households more than poorer ones because higher-income earners generally consumed more fuel and energy.
In an illustrative scenario presented in the regional outlook, the IMF estimated that general fuel-price smoothing could cost about four per cent of gross domestic product (GDP). By contrast, targeted transfers providing the same benefit to the poorest 40 per cent of the population would cost no more than 0.5 per cent of GDP.
Zeidane said governments could consider alternatives such as school feeding and other targeted assistance where systems for identifying beneficiaries were weak.
He added that any temporary price relief should be transparently funded, limited in scope and time-bound.
The Fund said savings from subsidy reforms should be directed towards people who need assistance rather than being used to subsidise products in ways that weaken public finances.
Mlachila said Nigeria was benefiting from higher international oil prices, which had increased foreign exchange earnings and supported the accumulation of external reserves.
He said the improved foreign exchange position had also increased liquidity in the economy, helping to support growth.
The IMF’s assessment points to the importance of managing additional oil earnings carefully, particularly as the government faces competing demands for public services, infrastructure and debt payments.
Mlachila also identified the services sector as a major driver of Nigeria’s growth, alongside the benefits of the improved external environment.
Zeidane said Nigeria’s large market, young entrepreneurs and technology-aware population offered considerable opportunities for private investment.
However, he said the country needed to improve governance, strengthen the business environment and deepen its integration with international markets to unlock that potential.
He said reforms in these areas could accelerate economic growth and create jobs, particularly if they encouraged businesses to invest and expand.
Zeidane also advised African countries, including Nigeria, to develop stronger domestic financing sources and deepen their financial markets to improve access to affordable capital.
He said pension funds, insurance companies and other institutional investors could help broaden domestic debt markets and provide additional financing for productive activities.
The IMF raised its economic growth forecast for Sub-Saharan Africa to 4.5 per cent in both 2026 and 2027, an increase of 0.2 percentage point from its April projection.
Mlachila said the region’s resilience reflected earlier economic reforms and the ability of governments and businesses to adjust to global disruptions.
The reforms included subsidy and exchange rate changes in Nigeria and Ethiopia, as well as structural reforms in South Africa.
Businesses had also adapted by changing their supply sources and transport arrangements, while countries adjusted to disruptions in global energy supplies.
The Fund said these measures had helped the region withstand economic pressures better than might otherwise have been expected.
Despite the improved growth outlook, Zeidane warned that African economies remained exposed to fresh economic shocks.
He said a renewed disruption to energy supplies, a sharp rise in global financial market uncertainty or a severe El Niño weather event could increase pressure on economies.
The Fund warned that the effects of higher commodity prices differed across countries. Oil, copper and gold exporters were benefiting from stronger prices, while economies less dependent on natural resources were experiencing slower growth and widening external deficits.
For Nigeria, higher oil prices provide support, but the IMF’s broader warning suggests that stronger export earnings alone cannot remove the risks associated with global uncertainty.
The IMF projected that median inflation in the region would rise from 3.4 per cent in 2025 to 4.3 per cent in 2026 and five per cent in 2027.
Zeidane said fuel and transport costs had already increased, while higher fertiliser prices could raise food production costs and threaten food security.
The pressure could be particularly difficult for households already struggling with the cost of living.
Although the figures are regional projections rather than forecasts for Nigeria alone, the risks are relevant to the country because higher fuel, transport and agricultural input costs can feed into food prices and other household expenses.
Zeidane said earlier fiscal adjustments had helped African countries reduce their budget deficits and debt ratios, but their ability to respond to new shocks remained limited.
Interest payments absorb about 13 per cent of government revenue in a typical country in the region, leaving less money for social services and public investment.
He said borrowing costs remained high even though some countries had continued to access international capital markets.
The IMF also warned that increased government borrowing from domestic banks could reduce credit available to businesses and deepen the link between government finances and the banking sector.
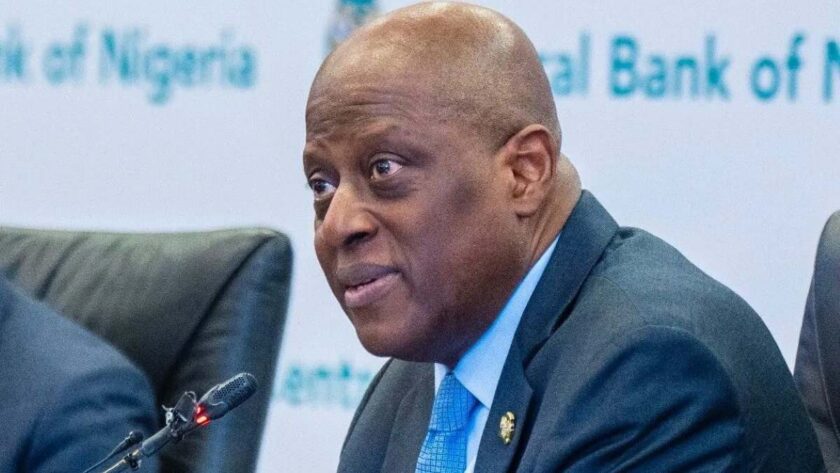
- Olayemi Cardoso, Governor, Central Bank of Nigeria
For Nigeria, the broader concern is the need to balance debt servicing with spending on infrastructure, education, healthcare and other productive activities.
Mlachila said countries across the region had issued about $12 billion in international bonds during the first nine months of the year.
He explained that economic reforms had helped several countries reduce the additional interest investors demanded to lend to them.
However, the benefit had been offset by rising benchmark interest rates, including an increase of more than 100 basis points in US 10-year Treasury yields during the period discussed.
The IMF advised governments to assess borrowing decisions individually, comparing the cost of international financing with alternative sources of funds.
It also recommended stronger economic fundamentals, better fiscal management and transparent debt reporting as ways to improve access to affordable borrowing.
Zeidane said bilateral aid to the region was projected to decline by a further 12 per cent in 2026, following a steep fall in the previous year.
He warned that reduced assistance would leave countries with less money to address economic shocks and finance development programmes.
The Fund said the reduction in aid, combined with rising borrowing costs and higher essential commodity prices, could make it more difficult for vulnerable economies to protect households and sustain investment.
Zeidane said African governments should manage immediate economic pressures without sacrificing investments needed to support future growth.
He said the region’s resilience was real, reflecting difficult reforms and businesses’ ability to adapt, but warned that current resilience should not come at the expense of future prosperity.
The IMF called for policies that protect vulnerable households, maintain economic stability and sustain productive investment.
Zeidane said governments needed to improve electricity supply, digital connectivity, workforce skills and the business environment to attract private capital and create jobs.
He added that regional trade and economic integration could expand markets for businesses and reduce exposure to imported fuel.
The IMF said general fuel-price smoothing could cost about four per cent of GDP in its illustrative scenario, compared with no more than 0.5 per cent of GDP for targeted transfers providing the same benefit to the poorest 40 per cent of the population.
Zeidane said governments should protect vulnerable households while ensuring that support programmes did not place excessive pressure on public finances.
Where reliable systems for identifying beneficiaries were unavailable, the Fund suggested alternatives such as school feeding and other targeted forms of assistance.
It said any temporary price relief should be transparently funded and subject to clear limits and an end date.
Zeidane advised countries benefiting from higher commodity prices to save most of the additional revenue and consider using some of it to repay expensive debt.
Countries experiencing capital outflows, meanwhile, were advised to continue adjusting their public finances while protecting essential services and productive investment.
The recommendation is relevant to Nigeria because higher oil prices could generate additional revenue that could help strengthen public finances and reduce borrowing pressures.
The Fund said some African countries might need to tighten monetary policy to prevent temporary price increases from becoming persistent inflation.
Zeidane also said exchange rate flexibility, where permitted by national policy frameworks, could help countries absorb external shocks and preserve foreign reserves.
The recommendation was directed at the region as a whole. The representative separately described Nigeria’s gradual interest-rate reduction as appropriate because inflation had declined, while noting that the overall monetary policy stance remained tight.
Zeidane called for greater transparency in public debt and stronger debt management to help countries improve their access to financing.
He said sound economic fundamentals, credible fiscal policies and reliable debt information would help investors assess countries’ ability to repay their obligations.
The Fund also advised countries to develop domestic debt markets by broadening the participation of pension funds, insurance companies and other institutional investors.
It said deeper local-currency markets could give governments and businesses more financing options and reduce dependence on external borrowing.
Zeidane said African countries needed more reliable electricity, better digital connectivity, stronger workforce skills and a more predictable business environment.
He said these improvements could attract private investment, increase productivity and create jobs.
The Fund also called for deeper regional trade and economic integration to expand markets and reduce countries’ exposure to imported fuel.
It said such reforms were particularly important because Africa continued to face a substantial productivity gap compared with other emerging and developing economies.
The IMF said wider adoption of artificial intelligence (AI) could increase economic growth in Sub-Saharan Africa by more than four percentage points over 10 years.
Mlachila explained that this could translate into an additional 0.4 percentage point of growth annually if countries adopted and expanded the use of the technology.
He said the opportunity was not limited to countries producing AI technology. African economies could also benefit by applying AI to improve productivity in existing industries and public services.
The IMF identified agriculture, education, healthcare and government services as areas where the technology could make a difference.
Mlachila said agriculture offered considerable opportunities for AI because productivity and crop yields in the region remained below international levels.
The technology could help improve agricultural practices and support more efficient delivery of education, healthcare and government services.
For Nigeria, wider adoption could create opportunities to improve farm productivity, strengthen public service delivery and support businesses using digital technologies.
However, these gains would depend on countries addressing gaps in infrastructure, internet access and technical skills.
Mlachila said African countries exporting critical minerals could benefit from rising demand associated with the energy transition and the infrastructure required to support AI technology.
He said Africa held about 30 per cent of the world’s stock of critical minerals and identified the Democratic Republic of Congo as one country with potential to benefit.
The remarks did not provide a specific estimate of the potential gains for Nigeria. However, the issue is relevant to Nigeria’s efforts to develop its solid minerals industry and attract investment into mineral exploration and processing.
Zeidane said the IMF’s previous regional analysis estimated that Africa’s GDP could increase by more than 20 per cent over five to 10 years if countries closed half of the gap with comparator economies in governance, the business environment and international integration.
He said the potential gains could support faster growth, more jobs and greater prosperity.
For Nigeria, the findings point to the importance of improving the conditions under which businesses operate, strengthening institutions and making it easier for local firms to compete in international markets.
Zeidane said Africa’s fast-growing young population could help position the continent as a future driver of global economic growth.
He said this potential would depend on countries mobilising more capital, improving their ability to channel domestic savings into productive investment and making their economies more attractive to private investors.
The Fund said reforms that improve productivity and encourage businesses to invest would help translate demographic growth into employment and higher living standards.
The IMF said African countries needed to look beyond foreign capital and make better use of domestic savings to finance development.
Zeidane said pension funds, insurance companies and other institutional investors could help deepen domestic financial markets and provide longer-term financing.
The recommendation is relevant to Nigeria’s capital market and institutional investment sector, where domestic savings could help finance productive businesses and infrastructure.
The IMF said African countries entered the latest economic shock with stronger economic buffers following reforms undertaken in previous years.
Mlachila said the region had recorded its fastest growth in more than a decade by the end of 2025, alongside improvements in fiscal balances, debt stabilisation, inflation and current account positions.
He said these gains had helped countries absorb some of the pressure from the global economic environment.
Zeidane said businesses had responded to disruptions in global energy supplies by changing their sourcing arrangements and logistics and drawing down inventories.
He said these adjustments had helped maintain economic activity despite disruptions to supply chains.
The remarks suggested that the ability of businesses to adapt had been an important part of the region’s resilience.
Zeidane said the IMF would continue to support countries across the region through financial assistance, policy advice and capacity development tailored to their individual circumstances.
He said the Fund’s support would help countries address immediate economic pressures while strengthening their ability to withstand future shocks.
He concluded that Africa’s resilience needed to be sustained through policies that protect vulnerable people, maintain economic stability and preserve investment in long-term growth.






Financial technology (fintech) platform PalmPay has reinforced its commitment to responsible data governance and customer information protection.
This it did through a specialised two-day data protection workshop for employees and the launch of its internal Privacy Champions Programme, an initiative designed to strengthen awareness, accountability, and responsible data handling across the organisation.
The initiative comes at a time when data protection is increasingly critical following recent recorded 281,500 compromised user accounts in the first quarter of 2026, ranking 34th among the world’s most breached countries, according to a new quarterly data breach analysis by cybersecurity firm, Surfshark.
Facilitated by the Nigeria Data Protection Commission (NDPC) and leading Data Protection Compliance Organisation (DPCO) TechHive Advisory, the two-day workshop equipped employees with practical knowledge on privacy governance and data protection obligations, incident awareness, and the role each employee plays in protecting personal data.
The initiative forms part of PalmPay’s on-going efforts to advance compliance with the Nigeria Data Protection Act (NDPA) 2023. It also reflects the company’s continued investment in safeguarding customer information and fostering a culture where privacy remains everyone’s responsibility.
The Privacy Champions Programme establishes a network of employee representatives across business functions that will support awareness, promote best practices and help strengthen the organisation’s privacy culture.
By integrating privacy considerations into day-to–day activities the initiative aims to further enhance accountability and reinforces customer trust.
Speaking on the initiative, Managing Director of PalmPay, Chika Nwosu, stated: “At PalmPay, protecting customer information is fundamental to maintaining the trust our customers place in us every day, and remains central to our operations.
“Statistically, 10 out of 100 Nigerians have been affected by data breaches. Hence, we have a greater responsibility to ensure that personal information is collected, processed, stored, and protected responsibly.
“This specialised training reflects our continued investment in strengthening internal awareness and ensuring our teams remain equipped to uphold the highest standards of data privacy and protection.”
As a digital financial services platform serving millions of users, PalmPay reaffirmed that privacy and data protection remain embedded in its operational culture, with continuous investments in data governance practices.
PalmPay also encourages customers to remain vigilant and adopt safe digital practices, including protecting account credentials, exercising caution when sharing personal information online, and reporting suspicious activities promptly.
Nwosu maintained that building a secure digital ecosystem requires a shared commitment from organisations, regulators, and users alike.
LECON Finance Company Limited, a Central Bank of Nigeria (CBN)-licensed finance company, says it has disbursed over N30 billion in leases to businesses nationwide.
This achievement reinforces its pivotal role in powering Nigeria’s productive sectors and expanding the country’s leasing ecosystem.
“Since inception, we have financed over 2,000 projects across key industries including agriculture, healthcare, logistics, manufacturing, education, transportation, construction, and renewable energy. In the last five years alone, the company has supported more than 230 projects, enabling enterprises to acquire vital equipment and assets that enhance productivity, drive innovation, and create jobs,” it said in a statement.
Through its strategic leasing and financing solutions, LECON has emerged as a catalyst for inclusive and sustainable economic growth. The company focuses on sectors critical to Nigeria’s long-term prosperity — food and agro-processing, mining and solid minerals, renewable energy and climate, healthcare and pharmaceuticals, ICT and telecommunications, and women-led enterprises.
By making productive assets accessible to smallholder farmers, schools, healthcare providers, transport operators, and emerging entrepreneurs, LECON is closing the financing gap that limits the potential of underserved groups. These interventions are transforming local industries and boosting Nigeria’s productivity.
Reaffirming LECON’s dedication to making leasing available to businesses, the Managing Director/CEO, Mrs. Ebehiriere Ehi-Omoike, said “we are on a mission to democratize access to productive assets for businesses of all sizes to create real impact. These milestones reflect our dedication to building a resilient and inclusive financial ecosystem,”
As one of the earliest institutions in Nigeria’s leasing industry, LECON remains a cornerstone of Nigeria’s leasing ecosytem having been instrumental in legitimizing leasing as a credible and effective financing tool for large corporates and MSMEs alike.
By offering flexible, asset-backed financing, LECON empowers businesses to invest in modern equipment without the heavy burden of upfront capital costs. This model has strengthened confidence in leasing as a sustainable growth instrument, helping enterprises expand and thrive.
The company continues to shape Nigeria’s leasing landscape through thought leadership and active participation in the Equipment Leasing Association of Nigeria (ELAN), where it is a pioneer member.
LECON’s strong institutional credibility and financial strength anchors its reputation for sound governance, risk management, and operational discipline which has earned it a consistent “A+” credit rating from Agusto & Co., thus confirming its robust financial health and institutional resilience.
As a CBN-licensed finance company and a subsidiary of the Bank of Industry (BOI), LECON operates with full regulatory compliance and a clear mandate to deliver financial solutions that promote inclusive growth and national development.
LECON’s heritage spans more than five decades. Established in 1970 under Nigeria’s indigenization policy as the Commonwealth Development Corporation (CDC), it was later acquired as a wholly owned subsidiary of the Nigerian Industrial Development Bank Limited (NIDB) — the precursor to today’s Bank of Industry (BOI).
In 1989, it became the Leasing Company of Nigeria (LECON) to reflect its focus on leasing. In 2022, the pioneer institution was rebranded as a legacy institution with a modern vision to LECON Finance Company Limited, signaling a new era of transformation, growth, and broader financial inclusion.
LECON’s N30 billion lease portfolio represents more than financial success — it reflects tangible economic and social impact. Through its leasing operations, the company has facilitated job creation across key sectors, improved productivity for local enterprises, financial inclusion for underserved entrepreneurs and empowerment of women-led and youth-driven businesses
Its project portfolio covers agro and food processing, healthcare, petrochemicals, education, transport, logistics, manufacturing, construction, renewable energy, solid minerals, mining, and aviation with each project contributes to a more resilient, diversified Nigerian economy.
As Nigeria continues to pursue economic diversification, LECON remains committed to driving inclusive and sustainable financing. The company’s mission is to enable businesses — large and small — to access the productive assets they need to grow, compete, and create long-term value.
The International Monetary Fund (IMF) has called on governments worldwide to build stronger institutions and ensure the independence of their central banks.
At the IMF Annual Meetings in Washington, DC, IMF Managing Director Kristalina Georgieva spoke yesterday at the Civil Society Town Hall Programme, part of the pre-opening events at the ongoing World Bank/IMF Annual Meetings.
The IMF chief also played down the impact of US tariffs on many world economies, saying the effect of the tariffs has decreased compared with the position at the April 2025 meetings.
She added that the private sector is currently much stronger than it was in April, signalling improvement in global economic performance.
She further acknowledged the devastating impact of high debt levels on world economies, urging countries to pursue more growth to reduce the burden of debt on their economies.
“The impact of tariffs is not as dramatic as we feared. US tariffs are lower today than they were last April.
“Many countries have chosen not to retaliate and are avoiding tit-for-tat actions, which is protecting world trade.
“There should be concerted efforts to bring debts down and support global economic recoveries, even as there is a need to identify pathways to resolving the debt crisis,” she said.
Georgieva called on countries to grow out of debt and create more development opportunities.
Reflecting on global progress over the decades, she said: “The average person today is much better off than, say, 30 years ago, but the averages conceal deep undercurrents of marginalisation, discontent, and hardship.
“Many people in many places—especially the young—are taking their disappointment to the streets: from Lima to Rabat, from Paris to Nairobi, and from Kathmandu to Jakarta, all are demanding better opportunities.”
She noted that the most important discussions at the Annual Meetings will focus on the global economic impact of these transformative forces and the policy turbulence we are experiencing.
“How is the world economy coping? Short answer: better than feared, but worse than we need.
“When we met in April, many experts—not us—predicted a U.S. recession in the near term, with negative spillovers to the rest of the world.
“Instead, the U.S. economy, as well as many other advanced and emerging markets and some developing countries, have held up.
“As our World Economic Outlook will explain next week, we see global growth slowing only slightly this year and next. All signs point to a world economy that has generally withstood acute strains from multiple shocks,” she said.
According to her, the resilience of global economies is attributable to improved policy fundamentals, private sector adaptability, less severe tariff outcomes than initially feared—for now—and supportive financial conditions—as long as they hold.

-
 Energy11 months ago
Diesel falls to ₦979/L in Lagos
-
 Law & Crime11 months ago
EFCC vs Yahaya Bello: Court adjourns ₦80.2b alleged fraud trial to Nov 11
-
 Art & Life9 years ago
These ’90s fashion trends are making a comeback in 2017
-
Business9 years ago
The 9 worst mistakes you can ever make at work
-
Entertainment9 years ago
The final 6 ‘Game of Thrones’ episodes might feel like a full season
-
Art & Life9 years ago
According to Dior Couture, this taboo fashion accessory is back
-
Entertainment9 years ago
The old and New Edition cast comes together to perform
-
Entertainment9 years ago
Mod turns ‘Counter-Strike’ into a ‘Tekken’ clone with fighting chickens