Business
PwC strengthens Nigeria’s business with four new partners

PwC Nigeria has added four new partners across its advisory, assurance and tax and regulatory services in a move that strengthened the firm’s competitive advantages in the Nigerian market.
The four new Nigerian partners, which admission takes effect immediately, are part of PwC Africa’s admission of 20 new partners across the region.
The newly admitted partners included Adesola Abiodun, Advisory Services; Oluwadamilola Dada, Assurance Services; Ugochi Ndebbio, Tax and Regulatory Services and Emeka Chime, a partner under Tax and Regulatory Services.
PwC noted that their admission came at a pivotal moment as organisations navigate rapid technological disruption, evolving stakeholder expectations, and shifting regulatory and economic realities.
Country Senior Partner, PwC Nigeria, Sam Abu, said the new partners bring expertise and leadership needed to support organisations to thrive in the dynamic Nigerian environment.
He noted that this year’s partner admissions reflected PwC Africa’s continued commitment to diversity and inclusion, with women representing 55 per cent of the total cohort.
“I am delighted to welcome four new partners to our partnership in Nigeria. Their admission recognises years of exceptional performance and marks their rise to the highest level of the profession.
“Over the years, they have supported our clients and helped shape our people and our firm. As businesses navigate a world of accelerating change, they need trusted advisers who can help them respond with confidence.
“Our new partners bring the perspective and leadership to help clients build trust, reinvent, and unlock new opportunities for growth,” Abu said.
Abiodun is a Partner in PwC Nigeria’s Deals Advisory practice, where he drives the firm’s private capital raising transactions across private credit, private equity, sustainable finance as well as the performance and restructuring business.
He also supports on the end-to-end mergers and acquisition advisory business.
Abiodun advises clients on direct project funding, bridge financing, corporate funding, working capital solutions and mergers and acquisitions across multiple sectors.
With nearly two decades of professional experience, he has built and managed relationships with international, regional and domestic financial institutions, including development finance institutions, sovereign wealth funds, pension funds, insurance funds and other institutional investors.
He has led fundraising transactions exceeding $10 billion across multiple sectors. Prior to joining PwC, he worked at Infrastructure Credit Guarantee Company Limited, where he led strategic planning and execution of origination projects while managing investor relations, client relationships and market development activities.
He also worked at Vetiva Capital Management Limited, advising public and private sector clients on debt and equity capital raising, project finance, mergers and acquisitions, and divestments.
He holds a First-Class degree in Accounting from the University of Lagos and a Master’s degree in Accounting and Finance with Distinction from Alliance Manchester Business School, University of Manchester UK. He is a Fellow of the Institute of Chartered Accountants of Nigeria (ICAN).
As a Partner, Abiodun will continue to focus on helping clients access capital, lead the execution complex transactions across the deals cycle and unlock growth opportunities. He will also support the expansion of PwC’s Deals Advisory services across Nigeria and the West Market Area.
Dada is Partner in PwC Nigeria’s Assurance practice serving leading organisations across the energy, utilities and resources sectors in Nigeria and internationally.
She has extensive experience in audit and assurance, internal controls, financial reporting and risk management. Prior to joining PwC Nigeria, she worked with PwC USA, advising major utility and energy companies reporting under US GAAP, SEC and Sarbanes-Oxley frameworks. Throughout her career, she has held several leadership roles, including serving as Chief of Staff to the PwC Africa Assurance Leader.
Dada holds an MBA from Imperial College Business School, London, and is an Associate Chartered Accountant (ICAN), a Certified Public Accountant (Texas, USA), and holds the ACCA Diploma in International Financial Reporting Standards.
She has also advised boards, executive leadership teams, regulators and multinational organisations on compliance, financial reporting, controls transformation and business improvement initiatives.
Her areas of expertise included audit and assurance, Internal Control over Financial Reporting (ICFR), risk management, Sarbanes-Oxley compliance, and financial reporting under IFRS Accounting Standards and US GAAP.
She is recognised for helping organisations strengthen internal control environments, enhance financial reporting quality and build stakeholder confidence in complex and highly regulated industries.
As a Partner, Dada will focus on helping clients build trust through high-quality assurance, strong internal control frameworks and innovative risk management solutions.
She will also support the continued growth of PwC Nigeria’s energy, utilities and resources assurance practice, with a focus on advancing technology-enabled assurance and strengthening client relationships across the sector.
Ndebbio is a Partner in PwC Nigeria’s Tax and Regulatory Services practice and the driving force behind the firm’s Regulatory Business Solutions service line. Dual-qualified in law and accounting, she delivers comprehensive regulatory and tax compliance solutions to clients across a broad range of industries — spanning legal advisory, due diligence, health checks, transaction structuring, and access to tax and fiscal incentives.
Ndebbio also heads PwC Nigeria’s dispute resolution practice, representing clients before the Tax Appeal Tribunal, and champions the firm’s policy advocacy services — partnering with clients to produce data-driven reports and engage government authorities alongside industry stakeholders in pursuit of actionable solutions.
As General Counsel for PwC Nigeria, she provides strategic legal oversight across the full spectrum of the firm’s operational relationships, leading the in-house legal team to ensure sound legal governance at every level.
Ndebbio is a member of the Nigerian Bar Association (NBA), Association of Chartered Certified Accountants UK (ACCA), Institute of Chartered Accountants of Nigeria (ICAN), Institute of Chartered Secretaries and Administrators of Nigeria (ICSAN), and Chartered Institute of Taxation of Nigeria (CITN) — a multidisciplinary foundation that uniquely positions her to deliver integrated, commercially astute advice at the intersection of law, tax, and regulatory compliance.
As a Partner, Ndebbioi will continue to lead the Regulatory Business Solutions practice, serve as General Counsel for PwC Nigeria, and provide guidance on complex tax matters
Chime is a Partner in PwC Nigeria’s Tax and Regulatory Services practice with more than 16 years of experience advising local and multinational organisations on tax, regulatory and strategic business matters. Since joining PwC in 2010, Emeka has advised clients across a broad range of industries including consumer markets, financial services, oil and gas, and digital services.
He spent three years with PwC Houston, Texas, where he provided tax advisory services to private businesses and gained significant international tax experience.
His areas of expertise include tax structuring and advisory, international tax consulting, tax due diligence and mergers and acquisitions advisory, corporate and indirect tax consulting, business reorganisations, and corporate compliance services across various sectors. He has led numerous engagements involving investment structuring, transaction support, tax audits and market entry advisory.
Emeka is a Fellow of Association of Chartered Certified Accountants (ACCA), a Member of the Chartered Institute of Taxation of Nigeria (CITN) and holds an Executive Certification from the University of Southern California (USC).
As a Partner, Emeka will continue to support local and multinational businesses on complex tax and regulatory matters, helping organisations manage risk, navigate change and pursue growth opportunities with confidence.
Energy
Fed govt. rolls out one million CNG vehicles, intensifies CNG as cheaper transport alternative
By Oluwayanmife Lucas
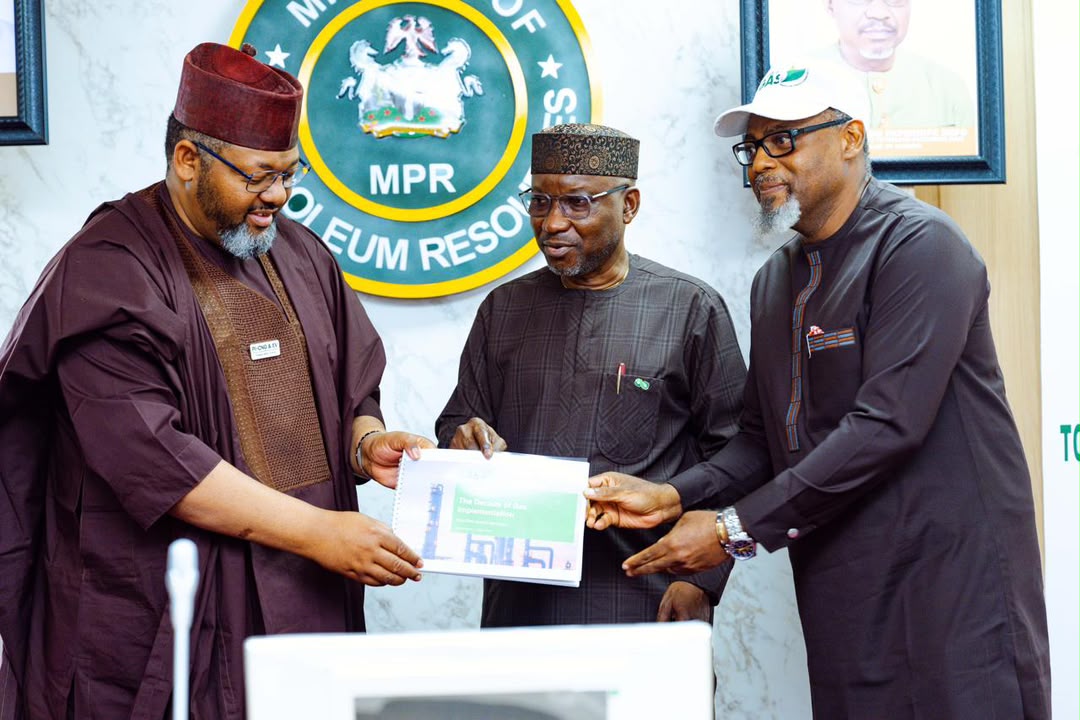
The Federal Government has pledged to intensify efforts to promote compressed natural gas (CNG) as a cheaper alternative fuel for transportation, with a renewed focus on accelerating the rollout of one million CNG-powered vehicles across the country.
To this end, the Minister of State Petroleum Resources (Gas), Ekperikpe Ekpo, has tasked the leadership of the Presidential Initiative on Compressed Natural Gas and Electric Vehicles (Pi-CNG & EV) and the Decade of Gas (DoGas) Secretariat to focus on critical interventions, step up investments, expand CNG infrastructure and strengthen programmes to drive nationwide adoption.
Ekpo gave the directive over the weekend in Abuja while receiving progress updates from the two bodies, stressing the need to translate the Federal Government’s Auto CNG policy into tangible benefits for Nigerians in form of cheaper transport fares.
He said the drive had become imperative following the removal of petrol subsidy and the need to provide Nigerians with a more affordable and environmentally friendly alternative for transportation, in line with the aspirations of President Bola Tinubu.
The Minister noted that Nigeria’s abundant natural gas resources presented an opportunity to lower transportation costs, deepen domestic gas utilisation and stimulate economic growth. He emphasised the need for sustained investments in refuelling infrastructure, vehicle conversions and other critical components required to accelerate CNG adoption.
Ekpo commended the leadership of Pi-CNG & EV for the progress recorded under its current management and assured the initiative of the government’s continued support in achieving its objectives, including the expansion of CNG use across the country.
He also highlighted the importance of growing domestic gas consumption, noting that supply had risen above two billion cubic feet per day for the first time in Nigeria history.
“Nigeria is a gas nation with a gas reserves index of over 80 years, and that is why we are talking about the Decade(s) of Gas.
“It is important that we listen to the directive of Mr. President to make transportation cheaper via CNG. We will continue to give you all the backing, to provide the necessary assistance to make sure we drive this project to a logical conclusion,” he said.
In his remarks, the Executive Chairman/CEO of Pi-CNG & EV, Ismaeel Ahmed, said the initiative would step up investments and programmes to expand CNG infrastructure and increase vehicle conversions nationwide and lead to chepaer ttansport fares for millions of Nigerians.
Ahmed explained that the joint industry market study completed by the decade of gas secretariat provides a framework for accelerating rollout, tracking progress, identifying gaps and strengthening implementation efforts to accelerate the adoption of CNG as a transportation fuel.
Similarly, the Coordinator of the Decade of Gas Secretariat, Mr. Ed Ubong, described CNG as a key component of Nigeria’s energy transition and assured continued support for the presidential initiative and efforts to increase domestic and export gas utilisation across the country for the benefits of Nigerians as well as investors.
By Our Correspondent
The International Monetary Fund (IMF) has backed the Central Bank of Nigeria’s gradual reduction of interest rates, saying the move is appropriate following significant progress in bringing inflation down, notwithstanding the fact that monetary policy remains tight.
The Fund also urged the Federal Government to increase revenue from non-oil sourcels to create more resources for education, healthcare and infrastructure, while pursuing reforms to attract private investment and create jobs.
The Director of the IMF’s African Department, Zeine Zeidane, gave the advice during the presentation of the Fund’s Regional Economic Outlook for Sub-Saharan Africa on the sidelines of the ongoing IMF/World Bank Annual Meetings in Bangkok, Thailand.
Zeidane said Nigeria had made significant progress in reducing inflation after a period of high price increases, creating room for some adjustment in monetary policy.
He described the decision to reduce interest rates as appropriate but cautioned against interpreting it as a move towards an accommodative monetary policy.
According to him, the overall policy stance remained tight, suggesting that the authorities were adjusting monetary conditions gradually rather than abandoning efforts to control inflation.
The position provides an important signal for businesses and investors as they assess the likely direction of borrowing costs, credit conditions and economic activity in Nigeria.
Speaking on the growth outlook, the Deputy Director of the IMF’s African Department, Montfort Mlachila, said Nigeria’s economy was benefiting from improved oil prices, stronger foreign exchange earnings, higher external reserves and increased liquidity.
Mlachila said the Fund had raised its growth forecast for Nigeria to 4.2 per cent in 2026 from four per cent previously, while projecting growth of 4.3 per cent in 2027.
He attributed the improved outlook partly to the more favourable external environment, increased foreign exchange availability, falling inflation and the performance of the services sector.
The IMF’s assessment suggests that stronger oil earnings and improving macroeconomic conditions are supporting economic activity, although sustaining growth will require reforms that broaden the sources of government revenue and attract more investment.
Zeidane advised the Federal Government to mobilise more revenue from outside the oil sector to strengthen public finances and provide more resources for essential services.
He said higher domestic revenue would create fiscal space for investment in education, healthcare and infrastructure.
The advice comes against the background of Nigeria’s exposure to fluctuations in international oil prices and competing demands on government revenue.
Zeidane also called for continued structural reforms to improve governance, the business environment and Nigeria’s integration with international markets.
He said Nigeria had a large market, a dynamic population, young entrepreneurs and a technology-aware workforce that could make it attractive to private investors.
However, he said these advantages needed to be supported by reforms that would make it easier for businesses to invest, expand and create jobs.
The IMF’s recommendations place domestic revenue mobilisation and private-sector investment at the centre of Nigeria’s efforts to sustain economic growth.
Zeidane advised Nigeria and other African countries to protect vulnerable households from rising living costs through targeted assistance rather than broad fuel-price subsidies.
He said general energy subsidies were expensive and often benefited wealthier households more than poorer ones because higher-income earners generally consumed more fuel and energy.
In an illustrative scenario presented in the regional outlook, the IMF estimated that general fuel-price smoothing could cost about four per cent of gross domestic product (GDP). By contrast, targeted transfers providing the same benefit to the poorest 40 per cent of the population would cost no more than 0.5 per cent of GDP.
Zeidane said governments could consider alternatives such as school feeding and other targeted assistance where systems for identifying beneficiaries were weak.
He added that any temporary price relief should be transparently funded, limited in scope and time-bound.
The Fund said savings from subsidy reforms should be directed towards people who need assistance rather than being used to subsidise products in ways that weaken public finances.
Mlachila said Nigeria was benefiting from higher international oil prices, which had increased foreign exchange earnings and supported the accumulation of external reserves.
He said the improved foreign exchange position had also increased liquidity in the economy, helping to support growth.
The IMF’s assessment points to the importance of managing additional oil earnings carefully, particularly as the government faces competing demands for public services, infrastructure and debt payments.
Mlachila also identified the services sector as a major driver of Nigeria’s growth, alongside the benefits of the improved external environment.
Zeidane said Nigeria’s large market, young entrepreneurs and technology-aware population offered considerable opportunities for private investment.
However, he said the country needed to improve governance, strengthen the business environment and deepen its integration with international markets to unlock that potential.
He said reforms in these areas could accelerate economic growth and create jobs, particularly if they encouraged businesses to invest and expand.
Zeidane also advised African countries, including Nigeria, to develop stronger domestic financing sources and deepen their financial markets to improve access to affordable capital.
He said pension funds, insurance companies and other institutional investors could help broaden domestic debt markets and provide additional financing for productive activities.
The IMF raised its economic growth forecast for Sub-Saharan Africa to 4.5 per cent in both 2026 and 2027, an increase of 0.2 percentage point from its April projection.
Mlachila said the region’s resilience reflected earlier economic reforms and the ability of governments and businesses to adjust to global disruptions.
The reforms included subsidy and exchange rate changes in Nigeria and Ethiopia, as well as structural reforms in South Africa.
Businesses had also adapted by changing their supply sources and transport arrangements, while countries adjusted to disruptions in global energy supplies.
The Fund said these measures had helped the region withstand economic pressures better than might otherwise have been expected.
Despite the improved growth outlook, Zeidane warned that African economies remained exposed to fresh economic shocks.
He said a renewed disruption to energy supplies, a sharp rise in global financial market uncertainty or a severe El Niño weather event could increase pressure on economies.
The Fund warned that the effects of higher commodity prices differed across countries. Oil, copper and gold exporters were benefiting from stronger prices, while economies less dependent on natural resources were experiencing slower growth and widening external deficits.
For Nigeria, higher oil prices provide support, but the IMF’s broader warning suggests that stronger export earnings alone cannot remove the risks associated with global uncertainty.
The IMF projected that median inflation in the region would rise from 3.4 per cent in 2025 to 4.3 per cent in 2026 and five per cent in 2027.
Zeidane said fuel and transport costs had already increased, while higher fertiliser prices could raise food production costs and threaten food security.
The pressure could be particularly difficult for households already struggling with the cost of living.
Although the figures are regional projections rather than forecasts for Nigeria alone, the risks are relevant to the country because higher fuel, transport and agricultural input costs can feed into food prices and other household expenses.
Zeidane said earlier fiscal adjustments had helped African countries reduce their budget deficits and debt ratios, but their ability to respond to new shocks remained limited.
Interest payments absorb about 13 per cent of government revenue in a typical country in the region, leaving less money for social services and public investment.
He said borrowing costs remained high even though some countries had continued to access international capital markets.
The IMF also warned that increased government borrowing from domestic banks could reduce credit available to businesses and deepen the link between government finances and the banking sector.
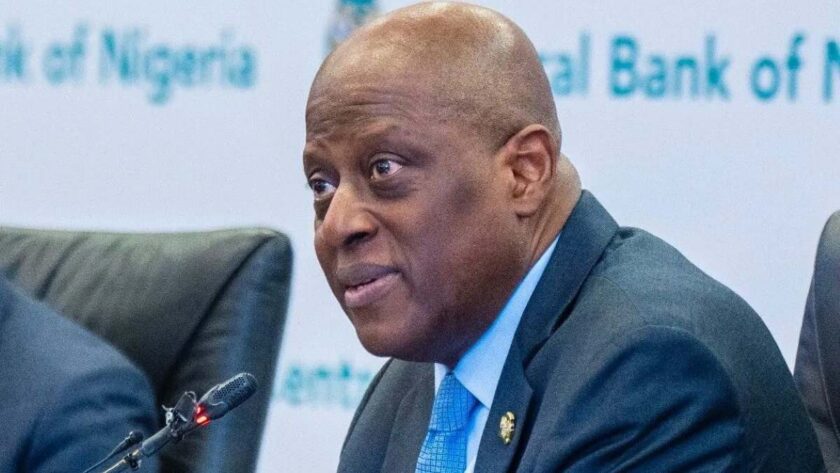
- Olayemi Cardoso, Governor, Central Bank of Nigeria
For Nigeria, the broader concern is the need to balance debt servicing with spending on infrastructure, education, healthcare and other productive activities.
Mlachila said countries across the region had issued about $12 billion in international bonds during the first nine months of the year.
He explained that economic reforms had helped several countries reduce the additional interest investors demanded to lend to them.
However, the benefit had been offset by rising benchmark interest rates, including an increase of more than 100 basis points in US 10-year Treasury yields during the period discussed.
The IMF advised governments to assess borrowing decisions individually, comparing the cost of international financing with alternative sources of funds.
It also recommended stronger economic fundamentals, better fiscal management and transparent debt reporting as ways to improve access to affordable borrowing.
Zeidane said bilateral aid to the region was projected to decline by a further 12 per cent in 2026, following a steep fall in the previous year.
He warned that reduced assistance would leave countries with less money to address economic shocks and finance development programmes.
The Fund said the reduction in aid, combined with rising borrowing costs and higher essential commodity prices, could make it more difficult for vulnerable economies to protect households and sustain investment.
Zeidane said African governments should manage immediate economic pressures without sacrificing investments needed to support future growth.
He said the region’s resilience was real, reflecting difficult reforms and businesses’ ability to adapt, but warned that current resilience should not come at the expense of future prosperity.
The IMF called for policies that protect vulnerable households, maintain economic stability and sustain productive investment.
Zeidane said governments needed to improve electricity supply, digital connectivity, workforce skills and the business environment to attract private capital and create jobs.
He added that regional trade and economic integration could expand markets for businesses and reduce exposure to imported fuel.
The IMF said general fuel-price smoothing could cost about four per cent of GDP in its illustrative scenario, compared with no more than 0.5 per cent of GDP for targeted transfers providing the same benefit to the poorest 40 per cent of the population.
Zeidane said governments should protect vulnerable households while ensuring that support programmes did not place excessive pressure on public finances.
Where reliable systems for identifying beneficiaries were unavailable, the Fund suggested alternatives such as school feeding and other targeted forms of assistance.
It said any temporary price relief should be transparently funded and subject to clear limits and an end date.
Zeidane advised countries benefiting from higher commodity prices to save most of the additional revenue and consider using some of it to repay expensive debt.
Countries experiencing capital outflows, meanwhile, were advised to continue adjusting their public finances while protecting essential services and productive investment.
The recommendation is relevant to Nigeria because higher oil prices could generate additional revenue that could help strengthen public finances and reduce borrowing pressures.
The Fund said some African countries might need to tighten monetary policy to prevent temporary price increases from becoming persistent inflation.
Zeidane also said exchange rate flexibility, where permitted by national policy frameworks, could help countries absorb external shocks and preserve foreign reserves.
The recommendation was directed at the region as a whole. The representative separately described Nigeria’s gradual interest-rate reduction as appropriate because inflation had declined, while noting that the overall monetary policy stance remained tight.
Zeidane called for greater transparency in public debt and stronger debt management to help countries improve their access to financing.
He said sound economic fundamentals, credible fiscal policies and reliable debt information would help investors assess countries’ ability to repay their obligations.
The Fund also advised countries to develop domestic debt markets by broadening the participation of pension funds, insurance companies and other institutional investors.
It said deeper local-currency markets could give governments and businesses more financing options and reduce dependence on external borrowing.
Zeidane said African countries needed more reliable electricity, better digital connectivity, stronger workforce skills and a more predictable business environment.
He said these improvements could attract private investment, increase productivity and create jobs.
The Fund also called for deeper regional trade and economic integration to expand markets and reduce countries’ exposure to imported fuel.
It said such reforms were particularly important because Africa continued to face a substantial productivity gap compared with other emerging and developing economies.
The IMF said wider adoption of artificial intelligence (AI) could increase economic growth in Sub-Saharan Africa by more than four percentage points over 10 years.
Mlachila explained that this could translate into an additional 0.4 percentage point of growth annually if countries adopted and expanded the use of the technology.
He said the opportunity was not limited to countries producing AI technology. African economies could also benefit by applying AI to improve productivity in existing industries and public services.
The IMF identified agriculture, education, healthcare and government services as areas where the technology could make a difference.
Mlachila said agriculture offered considerable opportunities for AI because productivity and crop yields in the region remained below international levels.
The technology could help improve agricultural practices and support more efficient delivery of education, healthcare and government services.
For Nigeria, wider adoption could create opportunities to improve farm productivity, strengthen public service delivery and support businesses using digital technologies.
However, these gains would depend on countries addressing gaps in infrastructure, internet access and technical skills.
Mlachila said African countries exporting critical minerals could benefit from rising demand associated with the energy transition and the infrastructure required to support AI technology.
He said Africa held about 30 per cent of the world’s stock of critical minerals and identified the Democratic Republic of Congo as one country with potential to benefit.
The remarks did not provide a specific estimate of the potential gains for Nigeria. However, the issue is relevant to Nigeria’s efforts to develop its solid minerals industry and attract investment into mineral exploration and processing.
Zeidane said the IMF’s previous regional analysis estimated that Africa’s GDP could increase by more than 20 per cent over five to 10 years if countries closed half of the gap with comparator economies in governance, the business environment and international integration.
He said the potential gains could support faster growth, more jobs and greater prosperity.
For Nigeria, the findings point to the importance of improving the conditions under which businesses operate, strengthening institutions and making it easier for local firms to compete in international markets.
Zeidane said Africa’s fast-growing young population could help position the continent as a future driver of global economic growth.
He said this potential would depend on countries mobilising more capital, improving their ability to channel domestic savings into productive investment and making their economies more attractive to private investors.
The Fund said reforms that improve productivity and encourage businesses to invest would help translate demographic growth into employment and higher living standards.
The IMF said African countries needed to look beyond foreign capital and make better use of domestic savings to finance development.
Zeidane said pension funds, insurance companies and other institutional investors could help deepen domestic financial markets and provide longer-term financing.
The recommendation is relevant to Nigeria’s capital market and institutional investment sector, where domestic savings could help finance productive businesses and infrastructure.
The IMF said African countries entered the latest economic shock with stronger economic buffers following reforms undertaken in previous years.
Mlachila said the region had recorded its fastest growth in more than a decade by the end of 2025, alongside improvements in fiscal balances, debt stabilisation, inflation and current account positions.
He said these gains had helped countries absorb some of the pressure from the global economic environment.
Zeidane said businesses had responded to disruptions in global energy supplies by changing their sourcing arrangements and logistics and drawing down inventories.
He said these adjustments had helped maintain economic activity despite disruptions to supply chains.
The remarks suggested that the ability of businesses to adapt had been an important part of the region’s resilience.
Zeidane said the IMF would continue to support countries across the region through financial assistance, policy advice and capacity development tailored to their individual circumstances.
He said the Fund’s support would help countries address immediate economic pressures while strengthening their ability to withstand future shocks.
He concluded that Africa’s resilience needed to be sustained through policies that protect vulnerable people, maintain economic stability and preserve investment in long-term growth.
· Revenue hits N3.74tr
By Oluwayanmife Lucas
The Nigerian National Petroleum Company (NNPC) Limited has announced a N431 billion Profit After Tax (PAT) for the month of August 2026. The figure shows a rise of 54.5 per cent from the N279 billion recorded in the previous month.
This was contained in the Company’s monthly operations and financial report for the month of August 2026.
Revenue for the period, according to the report, stood at N3.74 trillion as against N3.09 trillion recorded in the previous month.
The Company also recorded a 19.89 per cent increase in cumulative statutory payments from N7.91trillion for January to July to N9.49 trillion for January to August.
The report also put the average crude oil and gas production figures for the period at 1.69 million barrels per day and 7,680 million standard cubic feet per day, respectively.
On the state of infrastructure, there was 100per cent availability of upstream pipelines, while the OB3 and AKK Gas Pipelines stood at 100 per cent and 95 per cent completion.


-
 Energy11 months ago
Diesel falls to ₦979/L in Lagos
-
 Law & Crime12 months ago
EFCC vs Yahaya Bello: Court adjourns ₦80.2b alleged fraud trial to Nov 11
-
 Art & Life9 years ago
These ’90s fashion trends are making a comeback in 2017
-
Business9 years ago
The 9 worst mistakes you can ever make at work
-
Entertainment9 years ago
The final 6 ‘Game of Thrones’ episodes might feel like a full season
-
Art & Life9 years ago
According to Dior Couture, this taboo fashion accessory is back
-
Entertainment9 years ago
The old and New Edition cast comes together to perform
-
Entertainment9 years ago
Mod turns ‘Counter-Strike’ into a ‘Tekken’ clone with fighting chickens