Banking
Unity Bank–Providus Merger: Shareholders reveal decision-making date

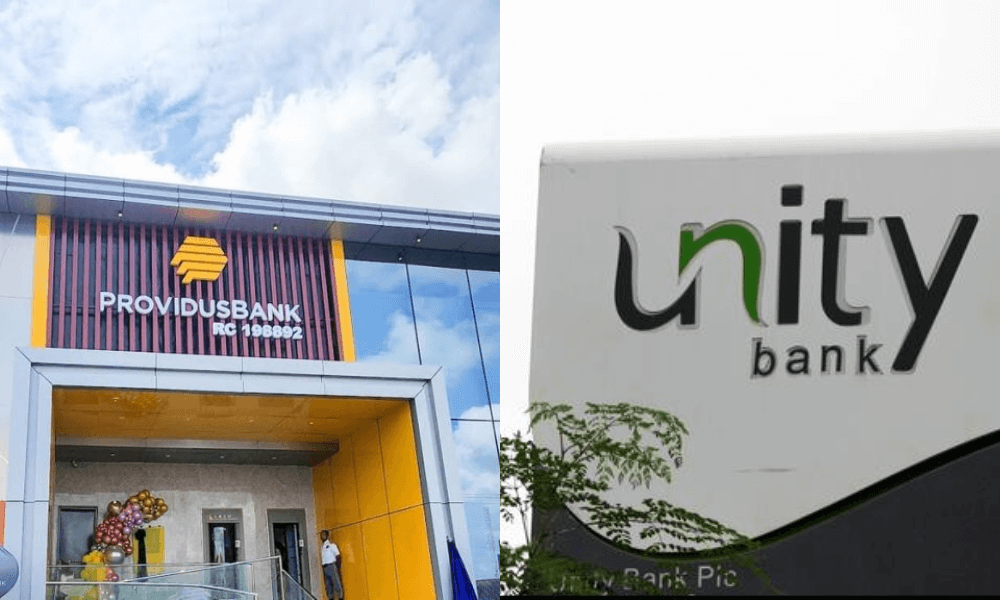
Unity Bank Plc has called a Court-Ordered Meeting for Friday, September 26, 2025 (9:00 a.m.) at OOPL Hotel, Abeokuta, Ogun State, to seek shareholder approval for a Scheme of Merger with ProvidusBank Limited.
The meeting follows an Order of the Federal High Court, Lagos Judicial Division, issued on July 17, 2025 by Hon. Justice D. I. Dipeolu under Section 711 of the Companies and Allied Matters Act (CAMA) 2020, in Suit No. FHC/L/MISC/734/2025.
The Scheme proposes the combination of all assets, liabilities, undertakings, real properties and intellectual property rights of Unity Bank with those of ProvidusBank. If sanctioned, ProvidusBank Limited will become the surviving entity, and Unity Bank’s entire share capital will be cancelled with the Bank dissolved without winding up.
The certificate of incorporation of ProvidusBank will stand as that of the enlarged institution.
Shareholders are to vote on the Scheme as set out in the Scheme Document dated June 25, 2025. The Scheme Consideration provides two alternatives for Unity Bank investors:
Cash: ₦3.18 per Unity Bank share; or
Share Swap: 18 ordinary shares of ₦0.50 each in ProvidusBank for every 17 ordinary shares of ₦0.50 each held in Unity Bank.
Approval of the Scheme at the meeting requires the statutory majority: not less than three-quarters in value of the ordinary shares of members present and voting by poll, in person or by proxy.
The Court has appointed Mr. Hafiz Mohammed Bashir, Chairman of the Board, to preside; failing him, Mr. Ebenezer A. Kolawole, Managing Director, or any other director chosen by shareholders present will chair the proceedings.
Shareholders may submit questions on the Scheme to the Company Secretary on or before 5:00 p.m., Tuesday, September 23, 2025.
Eligibility to attend and vote will be determined by the register of members as of Friday, September 19, 2025, after which the register will be closed for purposes of the meeting.
Proxy Forms have been circulated; duly executed and stamped forms (with any required Power of Attorney or notarized authority) should be lodged with the Registrar not less than 24 hours before the meeting.
In the event a member attends and votes in person, the proxy for that member will not be entitled to vote.
The Court’s Order also authorizes Unity Bank’s directors to consent to any modifications that the Securities and Exchange Commission (SEC), the Central Bank of Nigeria (CBN) and/or the Court may require.
Upon shareholder approval, Unity Bank’s solicitors—Adelepetun Caxton-Martins-Agbor & Segun (ACAS-Law)—will seek final Court sanction and any consequential orders necessary to give full effect to the Scheme, including the continuation of all pending or contemplated legal proceedings by or against ProvidusBank post-sanction.
Shareholders who have not received the Scheme Document within 14 days of the notice may obtain copies from Unity Bank Registrars Limited, 25 Ogunlana Drive, Surulere, Lagos. The Applicants to the proceedings are ProvidusBank Limited (RC 198892) and Unity Bank Plc (RC 94524).
Investors are advised to review the Scheme Document in detail and decide between the cash payout and the share-swap option, bearing in mind the approval thresholds, regulatory conditions, and the proposed corporate structure of the enlarged bank.
• Says $950m inflows from IMTOs, foreign portfolios hit $6.31b
• Lists banks’ roles in achieving $1tr economy by 2030
By Monireoluwa Lucas
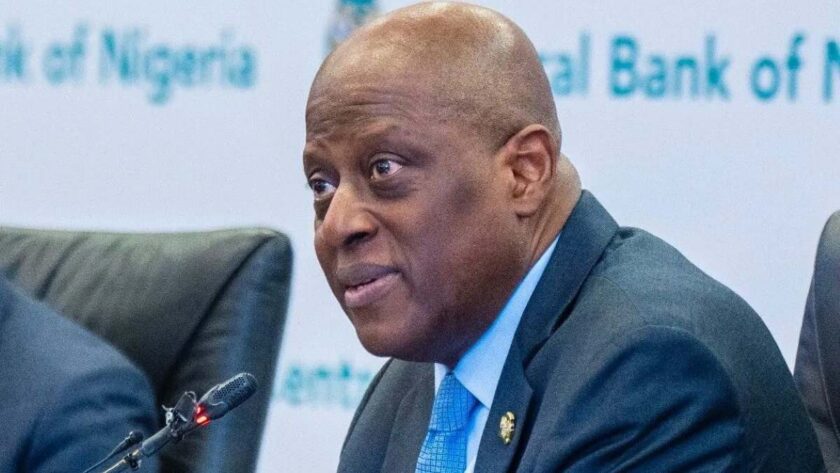
The Central Bank of Nigeria (CBN) today said sources of foreign exchange inflows into the economy has changed significantly, with autonomous sources taking the lead.
Speaking at the ongoing 38th FICAN conference held in Abuja, CBN Deputy Governor, Economic Policy, Dr. Muhammad Sani Abdullahi, disclosed that of the $10.82 billion in total inflows recorded in July 2026, $7.33 billion, or nearly 68 per cent, came from autonomous sources.
The breakdown showed that remittances through International Money Transfer Operators (IMTOs) reached $950 million that month while net foreign portfolio inflows totalled $6.31 billion in January to August 2026.
He explained that portfolio flows can reverse, but the broader improvement in supply has reduced the market’s reliance on direct CBN provision.
“Our external buffers are stronger. Gross reserves stood at US$55.60 billion on 11 September 2026, while the end-August stock provided 11.3 months of import cover,” he said.
Speaking on the theme: “Towards a Robust and Resilient Financial System in the Post-Banking Sector Recapitalisation”, he said Nigeria’s aspiration to build a $1 trillion economy by 2030 requires banks that are capable of mobilizing and allocating capital on a much larger scale.
Abdullahi, said stronger capital buffers should enable banks to finance local infrastructure, support industrial expansion, facilitate international trade, and compete more effectively in regional and global markets.
He said stronger banks also provide greater capacity to absorb losses during economic stress and sustain investment in innovation and digital transformation.
“The environment in which these banks operate is increasingly interconnected. Geopolitical uncertainty, climate-related risks, cyber threats, and rapid technological change can transmit shocks across borders through financial trade and technology, affecting capital flows, exchange rates, and external governments. Resilience, therefore, requires institutions to anticipate emerging risks, absorb shocks, adapt, and recover. The lessons of past financial crises underlie the value of aggregate capital, but also the need to prepare for risks that may take unfamiliar forms,” he said.
According to him, capital is therefore the starting point.
“Boards and management must maintain sound controls, recognize risks early, and learn to identify viable projects. Sound corporate governance must underpin that growth. Boards and management teams must demonstrate integrity, accountability, and transparency. Strengthen internal controls and guard against excessive restating. Their decisions must protect the interests of depositors, investors, and other stakeholders,” he said.
He directed that risk management be extended beyond credit risk to the market, utility, and operational risks, as well as cybersecurity, third-party dependencies, and private-related financial risks.
He said the environment in which these banks operate is increasingly interconnected.
“Geopolitical uncertainty, climate-related risks, cyber threats and rapid technological change can transmit shocks across borders through financial, trade and technology channels, affecting capital flows, exchange rates and external buffers.
“Resilience therefore requires institutions to anticipate emerging risks, absorb shocks, adapt and recover. The lessons of past financial crises underline the value of adequate capital, but also the need to prepare for risks that may take unfamiliar forms,” he said.
Abdullahi said the CBN will continue to pay close attention to governance, asset quality, liquidity and large exposures. “We will also expect banks to protect customer data, maintain reliable payment services and recover quickly from disruptions. A stronger balance sheet must be matched by stronger management of risk.
“As more financial services move to digital channels, banks must invest continuously in cybersecurity, data protection, disaster recovery and business continuity. Innovation brings opportunities, but public trust depends on customers being able to transact securely and access their funds reliably, including when systems come under pressure,” he said.
By Monireoluwa Lucas
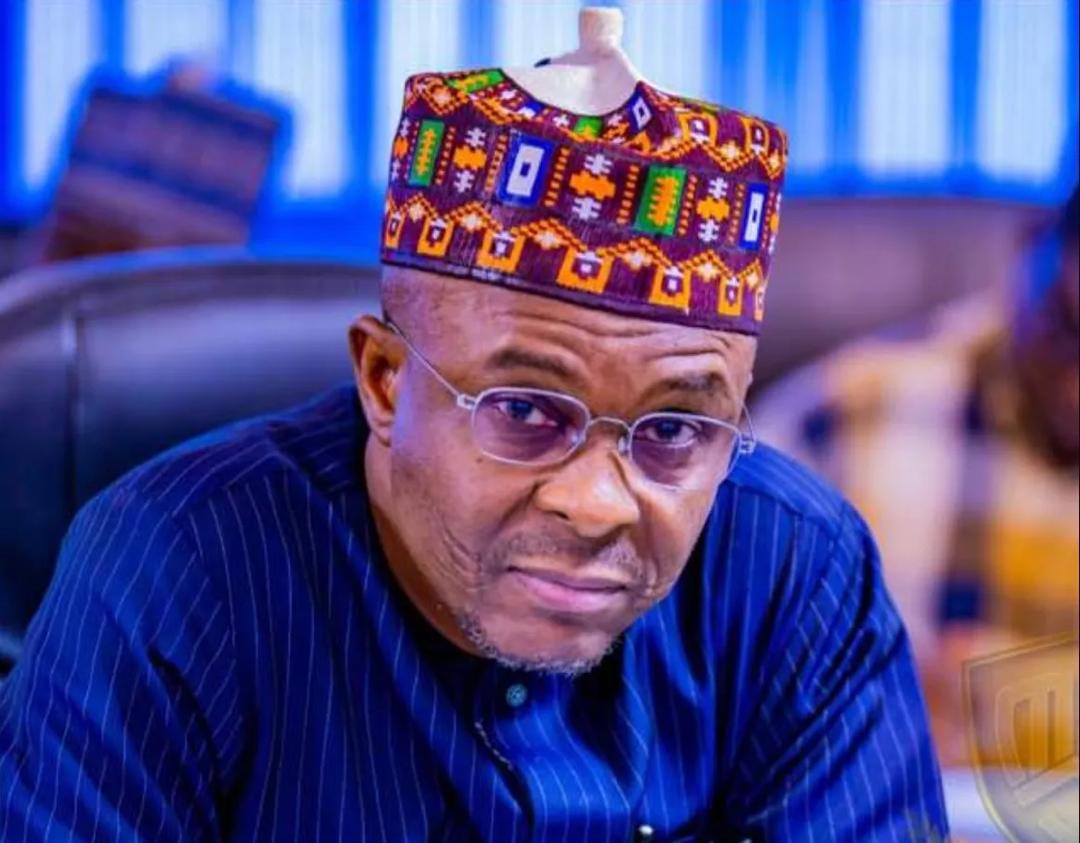
FirstBank has moved to equip small and medium-sized enterprises (SMEs) with practical strategies to win customers, increase sales and build sustainable businesses as it hosts the third-quarter edition of its SMEConnect Webinar on September 9, 2026.
The webinar, themed “The SME Growth Blueprint: Practical Sales Strategies to Win Customers and Boost Revenue,” is part of FirstBank’s capacity-building initiative aimed at helping entrepreneurs overcome some of the challenges limiting business growth and competitiveness.
The programme, anchored on the bank’s “You First” brand promise, is designed to provide business owners with practical knowledge, market insights and access to financial and advisory solutions tailored to their needs.
Participants are expected to gain insights into strategies for improving brand visibility, attracting and retaining customers, increasing sales conversion and building customer loyalty, with the broader objective of driving sustainable business growth.
The webinar will feature Chief Executive Officer and Founder, Bags Warehouse, Helen Mojisola Ijaola; Founder and Chief Executive Officer, Mamalicious Products Nigeria, Onome Gbenga-Adewara; and Group Head, Retail Banking Group, FirstBank, Olusola Ogunsakin.
Head, SME Banking, FirstBank, Helen A. Willie, will host the session, while Team Lead, SME Engagement & Advisory, FirstBank, Olajumoke Moyo-Ladipo, will serve as moderator.
Speaking ahead of the webinar, Group Executive, e-Business and Retail Products, FirstBank, Chuma Ezirim, said the ability of SMEs to develop effective sales strategies was critical to converting business opportunities into sustainable revenue.
He stated: “Growth is not accidental; it is driven by the ability of businesses to create value, win customers, and convert opportunities into sustainable revenue.
“At FirstBank, we recognise that many SMEs possess great products and services but often require practical sales strategies to unlock their full potential. This SMEConnect Webinar is designed to bridge that gap by providing insights from successful business leaders who have built and scaled thriving enterprises.Through these initiatives, we continue to demonstrate our commitment to equipping SMEs with the knowledge, capacity, and support needed to accelerate growth, create jobs, and strengthen Nigeria’s economy.”
SMEConnect is part of FirstBank’s broader efforts to support the growth and resilience of SMEs through capacity development, business advisory services and financial solutions.
- Withdraws operating licences
The Central Bank of Nigeria (CBN) has withdrawn the operating licences of 46 microfinance banks across the country, saying the affected institutions failed to meet the conditions required to continue operating as licensed financial institutions.
The decision took effect on July 1, 2026, following approval by the Governor of the Central Bank of Nigeria, Mr. Olayemi Cardoso.
A statement issued today by the Acting Director of Corporate Communications at the CBN, Mrs. Hakama Sidi-Ali, said the action was taken under the provisions of Sections 12 and 13 of the Banks and Other Financial Institutions Act (BOFIA), 2020, which empowers the apex bank to withdraw the licences of financial institutions that fail to comply with regulatory requirements.
According to the CBN, the affected banks were found to have breached one or more of the conditions required for continued operation.
The regulator explained that some of the institutions no longer had enough assets to cover their liabilities, while others shut down operations without obtaining approval from the Central Bank. It also said several of the banks had stopped carrying out financial intermediation, failed to begin operations within one year after receiving their licences, or could no longer maintain the minimum capital required by law because of accumulated losses.
“The revocation was approved by the Governor of the Central Bank of Nigeria, Mr. Olayemi Cardoso, following the banks’ failure to meet the regulatory requirements for continued operation as licensed financial institutions,” the statement said.
The affected institutions are Minji-Se Churchill Microfinance Bank in Rivers State, Merchant Microfinance Bank and Abia SME Microfinance Bank in Abia State, Janmaa Microfinance Bank in Kwara State, Busu Microfinance Bank and Bejin-Doko Microfinance Bank in Niger State, Gold Microfinance Bank, Chanelle Microfinance Bank, Safegate Microfinance Bank.
Others are, Supreme Microfinance Bank, Creditville Microfinance Bank, MBAG Microfinance Bank, Verdant Microfinance Bank and Entrepreneur Microfinance Bank in Lagos State, Zain Microfinance Bank (formerly Dawakin Tofa Microfinance Bank), Bompai Microfinance Bank, Ajwa Microfinance Bank (formerly Gezawa Microfinance Bank), Now Now Digital Microfinance Bank, Minjibir Microfinance Bank.
Also affected by the decision of the CBN are, Shanono Microfinance Bank, Sumaila Microfinance Bank, Rimin Gado Microfinance Bank, Sycamore Microfinance Bank, Tofa Microfinance Bank, Kanopoly Microfinance Bank, Bellbank Microfinance Bank (formerly Tsanyawa Microfinance Bank) and Esteem Microfinance Bank in Kano State, Crystabel Microfinance Bank in Bayelsa State, Kamba Microfinance Bank and Zuru Microfinance Bank in Kebbi State.
Iwade Microfinance Bank and Apple Microfinance Bank in Ogun State, Winview Microfinance Bank and Casha Microfinance Bank in the Federal Capital Territory, Mwaghavul Microfinance Bank and Yeneng Microfinance Bank in Plateau State, Creekline Microfinance Bank in Delta State, Bestar Microfinance Bank in Oyo State, Livingspring Microfinance Bank in Cross River State, Stanford Microfinance Bank in Akwa Ibom State all had their licences withdrawn.
The CBN hammer also fell on Frontline Microfinance Bank in Anambra State, Zafec Microfinance Bank and Basawa Microfinance Bank in Kaduna State, Straight Sahara Microfinance Bank in Benue State, OurPass Microfinance Bank in Ondo State, and Avantus Microfinance Bank in Osun State.
The apex bank said the exercise forms part of its ongoing efforts to strengthen Nigeria’s financial system by ensuring that only institutions that comply with banking regulations remain in operation.
It added that removing non-compliant institutions from the financial system would help protect depositors, promote stability in the banking sector and improve public confidence in licensed financial institutions.
The CBN said it remains committed to maintaining a safe, sound and resilient financial system and would continue to take supervisory and regulatory measures whenever necessary to ensure that banks and other financial institutions operate in line with existing laws and regulatory standards.
Industry observers say the latest action reflects the Central Bank’s resolve to tighten oversight of financial institutions and enforce compliance with prudential requirements aimed at safeguarding customers’ funds and preserving confidence in Nigeria’s banking sector.


-
 Energy11 months ago
Diesel falls to ₦979/L in Lagos
-
 Law & Crime12 months ago
EFCC vs Yahaya Bello: Court adjourns ₦80.2b alleged fraud trial to Nov 11
-
 Art & Life9 years ago
These ’90s fashion trends are making a comeback in 2017
-
Business9 years ago
The 9 worst mistakes you can ever make at work
-
Entertainment9 years ago
The final 6 ‘Game of Thrones’ episodes might feel like a full season
-
Art & Life9 years ago
According to Dior Couture, this taboo fashion accessory is back
-
Entertainment9 years ago
The old and New Edition cast comes together to perform
-
Entertainment9 years ago
Mod turns ‘Counter-Strike’ into a ‘Tekken’ clone with fighting chickens