Banking
FCMB Group plans second public offer in race for N500 billion recapitalisation

FCMB Group is turning to the market soon to source more cash in the second phase of the share sales that helped raise N147.5 billion from the public last year to further its recapitalisation goals.
The board of directors has shareholders’ backing from an extraordinary general meeting in December to proceed with the arrangement, the group disclosed on Friday, intending to announce the next move when the Securities and Exchange Commission, approves.
“The board is keen to commence the offer based on a live market price while ensuring that the Offer price reflects an appropriate discount,” a notification to the Nigerian Exchange stated
How much the banking group is looking to raise is still under wraps. Nevertheless, a resolution from the last December meeting has already given it the freedom to increase the target of its initial capital raise plan from N150 billion to N340 billion.
First City Monument Bank, the company’s commercial banking division, and other Nigerian lenders with overseas operations are required by the latest industry reforms to enlarge their paid-up capital to N500 billion not later than next March.
The tenfold increase from the previous threshold became an urgent requirement for the lenders after a series of devaluations and record inflationary pressures sharply eroded the time value of the naira between the last banking sector recapitalisation round in 2004 and now.
For that reason, the need for banks to create large buffers to augment core capital has become necessary to drive growth on a large scale and become competitive even within Africa, where it has now fallen to fourth place from being the biggest economy two years ago.
The Central Bank of Nigeria (CBN) said it is pushing ahead with higher capital requirements for banks with international, national and regional licenses as a major plank in the government’s goal of expanding the GDP to $1 trillion from $243 billion by 2030.
Commercial, merchant and non-interest banks are the categories affected by the new capital rules.
A company source, not wanting to be named, told PREMIUM TIMES that FCMB Group’s current capital has already surpassed the level required for national authorisation by virtue of its recent capital raise efforts, adding that the offer for subscription will take it closer to its target.
At the end of its last rate-setting meeting in July, the CBN stated that eight Nigerian banks have met the recapitalisation requirements so far.
• Says $950m inflows from IMTOs, foreign portfolios hit $6.31b
• Lists banks’ roles in achieving $1tr economy by 2030
By Monireoluwa Lucas
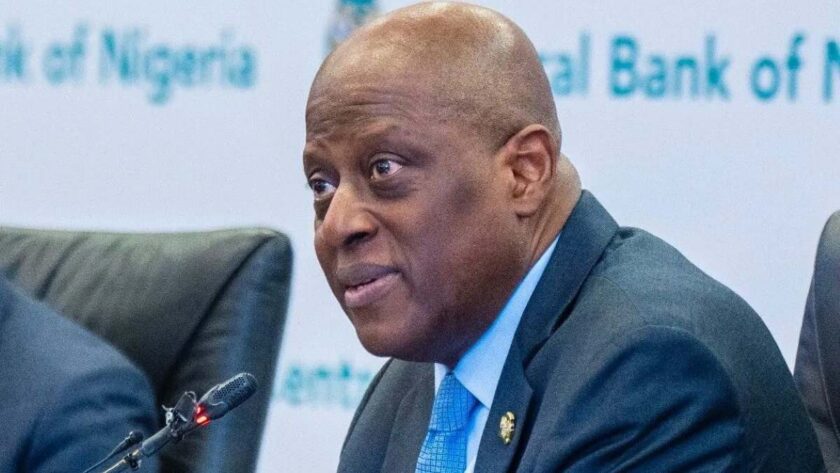
The Central Bank of Nigeria (CBN) today said sources of foreign exchange inflows into the economy has changed significantly, with autonomous sources taking the lead.
Speaking at the ongoing 38th FICAN conference held in Abuja, CBN Deputy Governor, Economic Policy, Dr. Muhammad Sani Abdullahi, disclosed that of the $10.82 billion in total inflows recorded in July 2026, $7.33 billion, or nearly 68 per cent, came from autonomous sources.
The breakdown showed that remittances through International Money Transfer Operators (IMTOs) reached $950 million that month while net foreign portfolio inflows totalled $6.31 billion in January to August 2026.
He explained that portfolio flows can reverse, but the broader improvement in supply has reduced the market’s reliance on direct CBN provision.
“Our external buffers are stronger. Gross reserves stood at US$55.60 billion on 11 September 2026, while the end-August stock provided 11.3 months of import cover,” he said.
Speaking on the theme: “Towards a Robust and Resilient Financial System in the Post-Banking Sector Recapitalisation”, he said Nigeria’s aspiration to build a $1 trillion economy by 2030 requires banks that are capable of mobilizing and allocating capital on a much larger scale.
Abdullahi, said stronger capital buffers should enable banks to finance local infrastructure, support industrial expansion, facilitate international trade, and compete more effectively in regional and global markets.
He said stronger banks also provide greater capacity to absorb losses during economic stress and sustain investment in innovation and digital transformation.
“The environment in which these banks operate is increasingly interconnected. Geopolitical uncertainty, climate-related risks, cyber threats, and rapid technological change can transmit shocks across borders through financial trade and technology, affecting capital flows, exchange rates, and external governments. Resilience, therefore, requires institutions to anticipate emerging risks, absorb shocks, adapt, and recover. The lessons of past financial crises underlie the value of aggregate capital, but also the need to prepare for risks that may take unfamiliar forms,” he said.
According to him, capital is therefore the starting point.
“Boards and management must maintain sound controls, recognize risks early, and learn to identify viable projects. Sound corporate governance must underpin that growth. Boards and management teams must demonstrate integrity, accountability, and transparency. Strengthen internal controls and guard against excessive restating. Their decisions must protect the interests of depositors, investors, and other stakeholders,” he said.
He directed that risk management be extended beyond credit risk to the market, utility, and operational risks, as well as cybersecurity, third-party dependencies, and private-related financial risks.
He said the environment in which these banks operate is increasingly interconnected.
“Geopolitical uncertainty, climate-related risks, cyber threats and rapid technological change can transmit shocks across borders through financial, trade and technology channels, affecting capital flows, exchange rates and external buffers.
“Resilience therefore requires institutions to anticipate emerging risks, absorb shocks, adapt and recover. The lessons of past financial crises underline the value of adequate capital, but also the need to prepare for risks that may take unfamiliar forms,” he said.
Abdullahi said the CBN will continue to pay close attention to governance, asset quality, liquidity and large exposures. “We will also expect banks to protect customer data, maintain reliable payment services and recover quickly from disruptions. A stronger balance sheet must be matched by stronger management of risk.
“As more financial services move to digital channels, banks must invest continuously in cybersecurity, data protection, disaster recovery and business continuity. Innovation brings opportunities, but public trust depends on customers being able to transact securely and access their funds reliably, including when systems come under pressure,” he said.
By Monireoluwa Lucas
FirstBank has moved to equip small and medium-sized enterprises (SMEs) with practical strategies to win customers, increase sales and build sustainable businesses as it hosts the third-quarter edition of its SMEConnect Webinar on September 9, 2026.
The webinar, themed “The SME Growth Blueprint: Practical Sales Strategies to Win Customers and Boost Revenue,” is part of FirstBank’s capacity-building initiative aimed at helping entrepreneurs overcome some of the challenges limiting business growth and competitiveness.
The programme, anchored on the bank’s “You First” brand promise, is designed to provide business owners with practical knowledge, market insights and access to financial and advisory solutions tailored to their needs.
Participants are expected to gain insights into strategies for improving brand visibility, attracting and retaining customers, increasing sales conversion and building customer loyalty, with the broader objective of driving sustainable business growth.
The webinar will feature Chief Executive Officer and Founder, Bags Warehouse, Helen Mojisola Ijaola; Founder and Chief Executive Officer, Mamalicious Products Nigeria, Onome Gbenga-Adewara; and Group Head, Retail Banking Group, FirstBank, Olusola Ogunsakin.
Head, SME Banking, FirstBank, Helen A. Willie, will host the session, while Team Lead, SME Engagement & Advisory, FirstBank, Olajumoke Moyo-Ladipo, will serve as moderator.
Speaking ahead of the webinar, Group Executive, e-Business and Retail Products, FirstBank, Chuma Ezirim, said the ability of SMEs to develop effective sales strategies was critical to converting business opportunities into sustainable revenue.
He stated: “Growth is not accidental; it is driven by the ability of businesses to create value, win customers, and convert opportunities into sustainable revenue.
“At FirstBank, we recognise that many SMEs possess great products and services but often require practical sales strategies to unlock their full potential. This SMEConnect Webinar is designed to bridge that gap by providing insights from successful business leaders who have built and scaled thriving enterprises.Through these initiatives, we continue to demonstrate our commitment to equipping SMEs with the knowledge, capacity, and support needed to accelerate growth, create jobs, and strengthen Nigeria’s economy.”
SMEConnect is part of FirstBank’s broader efforts to support the growth and resilience of SMEs through capacity development, business advisory services and financial solutions.
- Withdraws operating licences
The Central Bank of Nigeria (CBN) has withdrawn the operating licences of 46 microfinance banks across the country, saying the affected institutions failed to meet the conditions required to continue operating as licensed financial institutions.
The decision took effect on July 1, 2026, following approval by the Governor of the Central Bank of Nigeria, Mr. Olayemi Cardoso.
A statement issued today by the Acting Director of Corporate Communications at the CBN, Mrs. Hakama Sidi-Ali, said the action was taken under the provisions of Sections 12 and 13 of the Banks and Other Financial Institutions Act (BOFIA), 2020, which empowers the apex bank to withdraw the licences of financial institutions that fail to comply with regulatory requirements.
According to the CBN, the affected banks were found to have breached one or more of the conditions required for continued operation.
The regulator explained that some of the institutions no longer had enough assets to cover their liabilities, while others shut down operations without obtaining approval from the Central Bank. It also said several of the banks had stopped carrying out financial intermediation, failed to begin operations within one year after receiving their licences, or could no longer maintain the minimum capital required by law because of accumulated losses.
“The revocation was approved by the Governor of the Central Bank of Nigeria, Mr. Olayemi Cardoso, following the banks’ failure to meet the regulatory requirements for continued operation as licensed financial institutions,” the statement said.
The affected institutions are Minji-Se Churchill Microfinance Bank in Rivers State, Merchant Microfinance Bank and Abia SME Microfinance Bank in Abia State, Janmaa Microfinance Bank in Kwara State, Busu Microfinance Bank and Bejin-Doko Microfinance Bank in Niger State, Gold Microfinance Bank, Chanelle Microfinance Bank, Safegate Microfinance Bank.
Others are, Supreme Microfinance Bank, Creditville Microfinance Bank, MBAG Microfinance Bank, Verdant Microfinance Bank and Entrepreneur Microfinance Bank in Lagos State, Zain Microfinance Bank (formerly Dawakin Tofa Microfinance Bank), Bompai Microfinance Bank, Ajwa Microfinance Bank (formerly Gezawa Microfinance Bank), Now Now Digital Microfinance Bank, Minjibir Microfinance Bank.
Also affected by the decision of the CBN are, Shanono Microfinance Bank, Sumaila Microfinance Bank, Rimin Gado Microfinance Bank, Sycamore Microfinance Bank, Tofa Microfinance Bank, Kanopoly Microfinance Bank, Bellbank Microfinance Bank (formerly Tsanyawa Microfinance Bank) and Esteem Microfinance Bank in Kano State, Crystabel Microfinance Bank in Bayelsa State, Kamba Microfinance Bank and Zuru Microfinance Bank in Kebbi State.
Iwade Microfinance Bank and Apple Microfinance Bank in Ogun State, Winview Microfinance Bank and Casha Microfinance Bank in the Federal Capital Territory, Mwaghavul Microfinance Bank and Yeneng Microfinance Bank in Plateau State, Creekline Microfinance Bank in Delta State, Bestar Microfinance Bank in Oyo State, Livingspring Microfinance Bank in Cross River State, Stanford Microfinance Bank in Akwa Ibom State all had their licences withdrawn.
The CBN hammer also fell on Frontline Microfinance Bank in Anambra State, Zafec Microfinance Bank and Basawa Microfinance Bank in Kaduna State, Straight Sahara Microfinance Bank in Benue State, OurPass Microfinance Bank in Ondo State, and Avantus Microfinance Bank in Osun State.
The apex bank said the exercise forms part of its ongoing efforts to strengthen Nigeria’s financial system by ensuring that only institutions that comply with banking regulations remain in operation.
It added that removing non-compliant institutions from the financial system would help protect depositors, promote stability in the banking sector and improve public confidence in licensed financial institutions.
The CBN said it remains committed to maintaining a safe, sound and resilient financial system and would continue to take supervisory and regulatory measures whenever necessary to ensure that banks and other financial institutions operate in line with existing laws and regulatory standards.
Industry observers say the latest action reflects the Central Bank’s resolve to tighten oversight of financial institutions and enforce compliance with prudential requirements aimed at safeguarding customers’ funds and preserving confidence in Nigeria’s banking sector.


-
 Energy11 months ago
Diesel falls to ₦979/L in Lagos
-
 Law & Crime12 months ago
EFCC vs Yahaya Bello: Court adjourns ₦80.2b alleged fraud trial to Nov 11
-
 Art & Life9 years ago
These ’90s fashion trends are making a comeback in 2017
-
Business9 years ago
The 9 worst mistakes you can ever make at work
-
Entertainment9 years ago
The final 6 ‘Game of Thrones’ episodes might feel like a full season
-
Art & Life9 years ago
According to Dior Couture, this taboo fashion accessory is back
-
Entertainment9 years ago
The old and New Edition cast comes together to perform
-
Entertainment9 years ago
Mod turns ‘Counter-Strike’ into a ‘Tekken’ clone with fighting chickens
zoritoler imol
September 27, 2025 at 6:34 pm
Wow! Thank you! I continually wanted to write on my website something like that. Can I include a portion of your post to my blog?
The Trust News
September 28, 2025 at 5:13 am
Good morning Dear reader, Let me thank you for visiting our news site. We do not take this for granted. On your request, please take the content you wish for your use. Just help spread the good news about about our site…thetrustnews.com
thank you and have a beautiful sunday.