Economy
IMF Article IV report: Expert urges greater policy balance

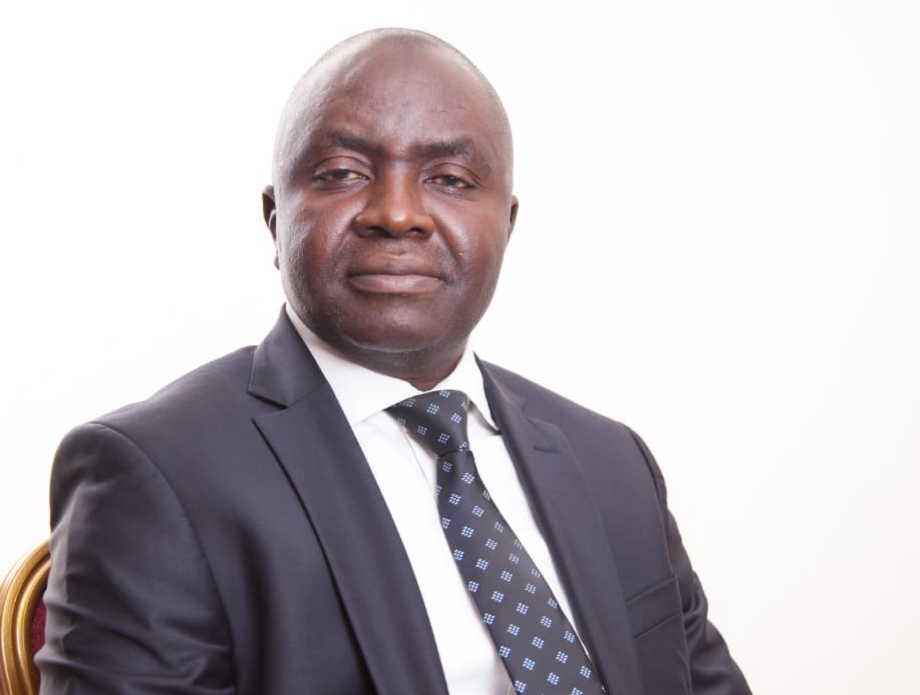
Nigeria’s positive assessment of her economic reforms by the International Monetary Fund (IMF) as contained in its Article IV Consultation Report, has drawn applause from economic expert and Chief executive Officer, Center for the Promotion of Private Enterprise (CPPE), Dr. Muda Yusuf.
He noted that the IMF’s acknowledgement of the progress made in restoring macroeconomic stability is broadly consistent with the position consistently advanced by CPPE and many stakeholders within the Nigerian private sector.
According to him, the reforms have helped to stabilise the foreign exchange market, improve external sector balances, strengthen investor confidence and restore a measure of policy credibility. Besides, Yusuf said the moderation in exchange rate volatility, the improvement in foreign reserves, the recovery in capital inflows and the stronger performance of many quoted companies underscore the positive outcomes of the stabilisation measures undertaken over the past three years.
“These gains are significant. After years of macroeconomic distortions, the economy is gradually moving from a regime of instability to one of greater predictability. This is an important foundation for investment, productivity and sustainable growth,” Dr. Yusuf said.
The CPPE, he said, equally agrees with the IMF’s concern about the persistence of poverty and food insecurity despite the progress made on macroeconomic stabilisation. This is because economic reforms are ultimately judged not only by their impact on macroeconomic indicators but by their ability to improve the welfare of citizens. He argued that while exchange rate stability, reserve accumulation and fiscal consolidation are important, however, he said, the true test of reform is whether they translate into lower food prices, better jobs, improved incomes and enhanced living standards.
He therefore proffered that the next phase of economic management should focus on converting macroeconomic gains into welfare gains, noting that the challenge before policymakers is no longer merely one of economic stabilisation but increasingly one of inclusive prosperity.
Yusuf warned of a situation that may lead to a risk of extreme monetary orthodoxy. According to him, while the IMF’s support for monetary tightening reflects conventional stabilisation thinking, he nonetheless expressed worries about the IMF’s continued emphasis on high interest rates without sufficient consideration of the adverse consequences for investment, enterprise growth, job creation and sovereign debt service pressures.
“The current monetary policy stance has delivered some benefits in terms of inflation moderation and exchange rate stability. However, every policy instrument has a point of diminishing returns. Beyond that point, the costs may begin to outweigh the benefits.
“The cost of credit in Nigeria has reached levels that are becoming increasingly prohibitive for productive investment. Lending rates remain among the highest in the world, making it difficult for businesses to expand, invest or create jobs.
“High yields on government securities have also intensified the crowding-out effect in the financial system. Banks and investors are increasingly channeling resources into treasury bills and government bonds rather than financing productive sectors of the economy. As a consequence, capital is gravitating towards financial assets rather than productive assets.
“An economy cannot achieve sustainable development when financial capital earns higher returns from government financial instruments than from supporting enterprise, innovation and industrialization,” Dr. Yusuf argued.
He also flayed the IMF for not sufficiently appreciating the developmental role of targeted financing interventions in an economy like Nigeria. He explained that development finance is not merely a policy choice, but an economic necessity. He warned that leaving such entirely to market forces, critical sectors such as agriculture, manufacturing, housing and infrastructure would remain chronically underfunded, thereby constraining productivity, job creation, industrialisation and long-term economic growth.
“Nigeria’s economic structure differs fundamentally from those of advanced economies. Strategic sectors such as agriculture, manufacturing, housing and infrastructure require long-term, patient capital which conventional market-based financing channels are often unable or unwilling to provide efficiently.
“In an economy where commercial lending is largely short-term, costly and risk-averse, development finance remains indispensable for unlocking productivity, supporting investment, expanding output and driving inclusive growth. A purely market-driven financing model cannot adequately address Nigeria’s structural financing gaps.
“Agriculture, for instance, cannot sustainably absorb commercial credit priced at prevailing market rates. Infrastructure projects often require financing tenors extending beyond what conventional banking structures can support.
“Development finance, therefore, should not be perceived as a distortion of the financial market; it is often a necessary response to market failure. Economic transformation has historically been supported by development finance institutions across both developed and emerging economies,” Dr. Yusuf warned.






The Federal Government’s revenue rose by 72 per cent to N6.2 trillion in the first half of 2026 from N3.6 trillion in the corresponding period of 2025, while interest payments increased by 38 per cent to N7.7 trillion from N5.6 trillion.
The Federal Ministry of Finance disclosed this on Sunday while responding to public commentary on the World Bank’s October 2026 Nigeria Development Update, which put federal interest payments at 124 per cent of revenue in the first half of this year.
The ministry said the growth in revenue had outpaced the increase in interest payments, reducing the interest-to-revenue ratio from 156 per cent in the first half of 2025 to 124 per cent in the corresponding period of 2026.
It added that the difference between interest payments and revenue narrowed from N2 trillion to N1.5 trillion within the period.
In a statement issued in Abuja, the ministry said the 124 per cent ratio did not present a complete picture of the government’s revenue position because some earnings were excluded from the calculation, while the interest figure covered obligations beyond the Federal Government alone.
According to the ministry, the interest payments include external loans obtained by state governments but serviced by the Federal Government.
It said comparing these obligations with federal revenue alone could overstate the ratio because the debt and revenue figures did not cover the same levels of government.
The ministry also said the revenue figure excluded independent income earned by government agencies and enterprises but not yet remitted to the Treasury.
It added that the timing of statutory tax payments affected the half-year figures, as some payments typically generate more revenue in the second half of the year.
The ministry cited the 2025 figures, saying the interest-to-revenue ratio stood at 156 per cent in the first half of that year but fell below 60 per cent for the full year. It also put the ratio at 97 per cent before the current administration’s reforms.
On the 2026 outlook, the ministry referred to the World Bank’s projection that Nigeria’s full-year debt service, covering both interest and principal repayments, would amount to 46 per cent of revenue.
The ministry said the full-year figure was a more appropriate measure for assessing the country’s debt-service position than a six-month comparison.
It maintained that all Federal Government borrowing was within the limits approved by the National Assembly under the 2026 Appropriation Act and the approved borrowing plan.
The statement added that the government’s borrowing complied with the Fiscal Responsibility Act 2007 and the Debt Management Office (Establishment) Act 2003.
It said the Debt Management Office regularly published information on government borrowing.
The ministry welcomed public scrutiny of government finances and urged analysts to compare revenue and debt figures covering the same levels of government and to consider the periods covered by the data.
It said the government remained open to requests for clarification on public finance figures.
The three tiers of government have shared N2.428 trillion revenue generated by the Federation in September 2026, according to the Federation Account Allocation Committee (FAAC).
The amount was shared at the committee’s October meeting in Abuja, with the Federal Government receiving N832.242 billion, state governments getting N799.872 billion and local government councils receiving N560.660 billion. The beneficiary states of the 13 percent derivative also received N236.049 billion as derivation revenue from mineral resources.
The Director of Press and Public Relations in the Office of the Accountant-General of the Federation (OAGF), Bawa Mokwa, disclosed this in a statement on the outcome of the meeting yesterday in Abuja.
The total distributable revenue comprised N1.672 trillion from statutory revenue and N756.587 billion from Value Added Tax (VAT).
According to the communiqué issued by FAAC, the Federation generated gross revenue of N3.913 trillion in September. However, N131.758 billion was deducted as the cost of collecting the revenue, while N1.352 trillion went into transfers, refunds and savings.
The figures show that the amount shared among the three tiers of government was lower than the gross revenue available for the month after the various deductions and other obligations were taken into account.
A breakdown of the statutory revenue showed that the Federal Government received N756.583 billion, while the state governments got N383.749 billion. The local government councils received N295.855 billion, while N236.049 billion was paid to the benefiting states as their 13 per cent derivation share of mineral revenue.
From the N756.587 billion distributable VAT revenue, the Federal Government received N75.659 billion, state governments got N416.123 billion and local government councils received N264.805 billion.
The allocation figures show that state governments and local government councils received the larger shares of the distributable VAT revenue, while the Federal Government received a smaller portion.
The communiqué also showed that gross statutory revenue rose in September, while VAT revenue declined during the period.
Gross statutory revenue stood at N3.096 trillion in September, compared with N2.850 trillion recorded in August. The increase of N246.384 billion represented a rise in revenue available from statutory sources.
In contrast, gross VAT revenue fell to N816.872 billion in September from N834.843 billion in August, representing a decline of N17.972 billion.
The difference in the performance of the two revenue sources means that the increase in statutory revenue was accompanied by a reduction in VAT receipts during the month.
FAAC attributed the changes in revenue performance to increases in some tax and petroleum-related revenue sources, alongside declines in others.
Petroleum Profit Tax, Hydrocarbon Tax, petroleum royalties, import duty, Common External Tariff (CET) levies and excise duty recorded significant increases in September.
However, Companies Income Tax (CIT), Capital Gains Tax (CGT), Stamp Duties Tax (SDT), VAT, mineral royalties, gas-flaring penalties, rental gas-flaring fees and miscellaneous oil revenue declined during the period.
By Oluwayanmife Lucas
Economic policy group and economist yesterday lent their support to the federal government’s decision to implement a temporary fuel price relief. They warned that this relief should not be misconstrued as return of subsidy on petroleum products, but be seen as a priority by government to protect vulnerable citizens, preserve the sustainability of public finances and maintain the integrity of ongoing economic reforms.
Besides, they warned that the commercial status of the Nigerian National Petroleum Company Limited (NNPC) Limited does not eliminate the government’s responsibility to respond to exceptional public-interest considerations.
NNPC Ltd., the group maintained, remains a government-owned commercial enterprise with a diversified portfolio of petroleum-related businesses, whose commercial mandate should ordinarily guide its operations. However, the policy group argued, temporary and clearly defined public-interest interventions can be accommodated within an appropriate governance framework.
The Group, Center for the promotion of Private Enterprise (CPPE), a policy and economic think-tank group, in a chat with The Nation yesterday, argued that the critical consideration is that such interventions must be transparent, proportionate, time-bound and financially sustainable.
The CPPE further noted that the current global energy crisis demands pragmatic policy responses, not ideological rigidity. It further argued that although economic reforms must remain sustainable, but they must also be responsive to the welfare of the people.
Therefore, it explained, Nigeria does not need a return to the “fiscally destructive” subsidy regime, but a credible framework for temporary, targeted and transparent social protection during exceptional economic shocks.
Speaking with exclusively The Trust News, the Chief Executive Officer, CPPE, Dr. Muda Yusuf, explained that economic policies are instruments for promoting citizens’ welfare; hence, they should not become rigid doctrines that prevent governments from responding to exceptional social and economic difficulties.
He noted that the current escalation in petroleum product prices is driven principally by developments in the global energy market, particularly geopolitical tensions that have pushed crude oil prices above $100 per barrel. He described this as an “external shock affecting both oil-producing and oil-importing economies; it is neither a consequence of Nigeria’s subsidy removal policy nor peculiar to the Nigerian economy.”
Dr. Yusuf warned against the misconception that the Federal Government’s recent fuel price relief initiative through the NNPC is a reversal of the petroleum subsidy removal policy. Such an interpretation, he argued, is misleading and fails to distinguish between a fundamental policy reversal and a temporary intervention in response to an extraordinary economic shock.
“Extraordinary economic circumstances sometimes require exceptional policy responses. Governments across the world have historically intervened to cushion households and businesses against severe external shocks without abandoning their underlying economic policy frameworks. The COVID-19 pandemic provided compelling evidence of this approach, even in advanced market economies.
“The intervention is substantially different in scale, design and potential fiscal implications from the previous subsidy regime. Its temporary character and limited market coverage are important distinctions,” Dr. Yusuf said.
According to him, the removal of the previous petroleum subsidy was a necessary structural reform, therefore, reinstating a broad-based consumption subsidy would recreate serious fiscal vulnerabilities and undermine the gains from economic reforms.
He explained further: “For illustration, a subsidy of ₦1,000 per litre on national consumption of 50 million litres daily would create a fiscal exposure of approximately ₦50 billion daily; ₦1.5 trillion monthly and ₦18.25 trillion annually. Such an obligation would be fiscally unsustainable, especially in an economy facing substantial infrastructure deficits, debt-service commitments and competing development priorities. However, a limited and temporary intervention should not automatically be interpreted as a deterioration in policy credibility.”
Dr. Yusuf, an economist, explained that investors are principally concerned about policy predictability, market access, commercial viability, fiscal sustainability and the protection of legitimate investments. These fundamentals, he said, need not be compromised by a narrowly targeted emergency relief measure.
In this regard, the CPPE argued that there is a need to have a critical distinction between the previous subsidy regime and the current intervention. Under the former subsidy arrangement, Dr. Yusuf said, government effectively carried a substantial fiscal burden on nationwide petrol consumption, estimated at various times at between 50 million and 80 million litres daily. This arrangement created enormous fiscal pressures, weakened public finances, crowded out development spending and contributed to macroeconomic instability.
Citing an illustrative calculation based on the volumes contained in the ministerial commentary; by contrast, he said, the current intervention covers approximately 70 million litres of NNPC fuel supply monthly, compared with estimated national petrol consumption of 50 million litres daily and an estimated national monthly consumption of 1.5 billion litres; while NNPC monthly volume under the intervention will be 70 million litres, translating to an estimated national consumption of 4.7 per cent
“Arising from these figures, an intervention covering less than five per cent of estimated national consumption cannot reasonably be equated with a nationwide subsidy regime. More importantly, the intervention does not reinstate an administered national petrol price, impose a general subsidy obligation on private operators or dismantle the market-oriented framework for petroleum product pricing.
“The appropriate questions should therefore concern the fiscal cost, transparency, duration, beneficiaries and effectiveness of the intervention, rather than an inaccurate characterisation of it as a wholesale policy reversal,” Dr. Yusuf argued.
But beyond fuel discounts, the CPPE said there is a need to addressing the wider social costs. It said that while the proposed fuel price relief is a welcome development, its limited coverage means that its aggregate impact on household welfare will also be limited.
Government, the group further highlighted, should pursue broader interventions that address the principal channels through which the energy price shock affects citizens.
In a four-point agenda, the CPPE said the government should scale up affordable mass transit, because transportation is one of the most immediate transmission channels of higher energy prices to household expenditure and business operating costs. To this end, the group said the federal and state governments should prioritise high-capacity buses, including CNG, electric and other economically viable alternatives.
Support for agricultural productivity and food supply, strengthening state and local government interventions by way of states designating discounted fuel outlets, limited emergency fuel allocations for essential services, like subsidised public transport and targeted support for vulnerable households, should be considered, as well as protecting the integrity of petroleum market reforms.
“Government should sustain market-based pricing, fair competition, transparent regulation and a trade policy framework that supports domestic refining investment. Emergency interventions should not become a pretext for arbitrary price controls or the reintroduction of opaque fiscal obligations,” Dr. Yusuf submitted.
-
 Energy11 months ago
Diesel falls to ₦979/L in Lagos
-
 Law & Crime12 months ago
EFCC vs Yahaya Bello: Court adjourns ₦80.2b alleged fraud trial to Nov 11
-
 Art & Life9 years ago
These ’90s fashion trends are making a comeback in 2017
-
Business9 years ago
The 9 worst mistakes you can ever make at work
-
Entertainment9 years ago
The final 6 ‘Game of Thrones’ episodes might feel like a full season
-
Art & Life9 years ago
According to Dior Couture, this taboo fashion accessory is back
-
Entertainment9 years ago
The old and New Edition cast comes together to perform
-
Entertainment9 years ago
Mod turns ‘Counter-Strike’ into a ‘Tekken’ clone with fighting chickens